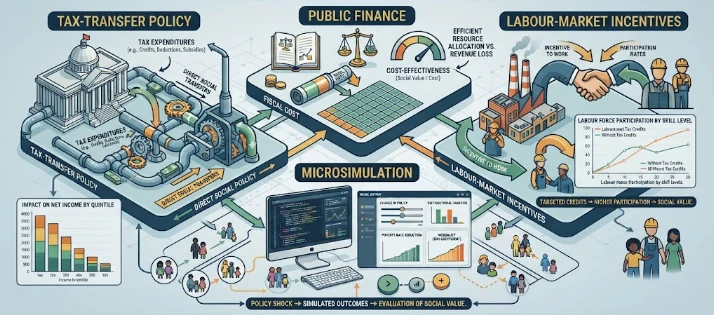
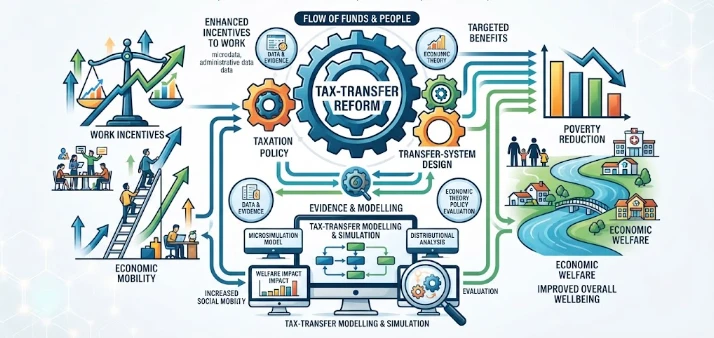
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
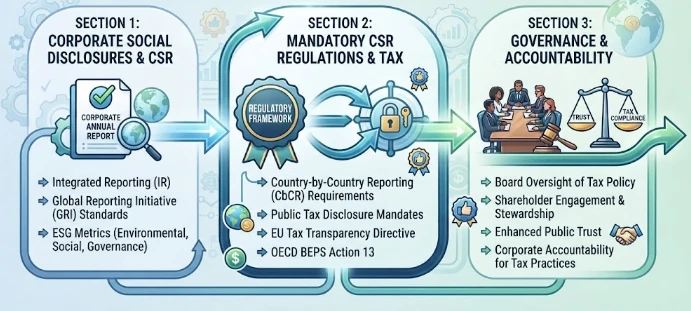
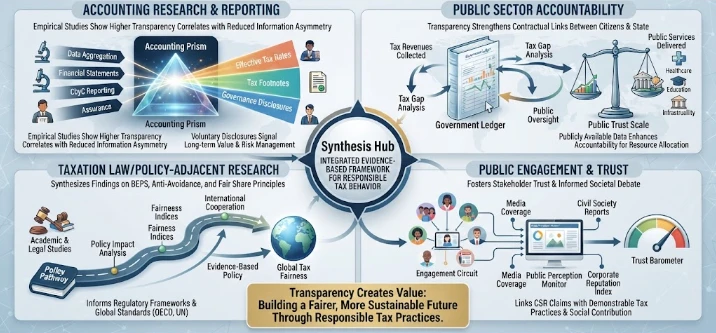
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life
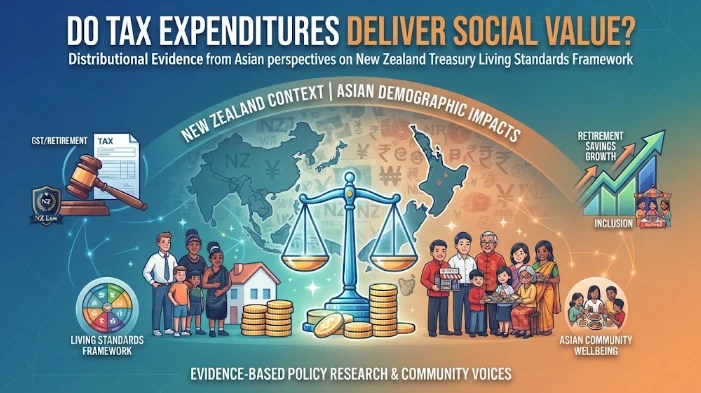
This article evaluates tax expenditures through a broader wellbeing and distributional framework, drawing on New Zealand’s Living Standards Framework, GST and retirement policy. It argues that fiscal analysis should not stop at annual income, revenue or GDP because concessions can affect consumption, saving, retirement security, housing, work, culture and resilience across generations. Distribution should therefore be examined by age, income, wealth and long-term wellbeing. Consumption taxes ill
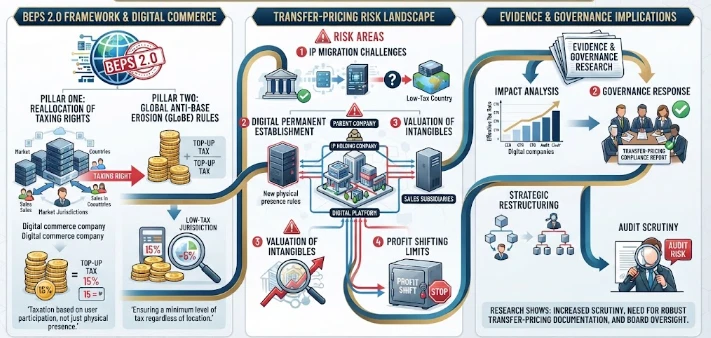
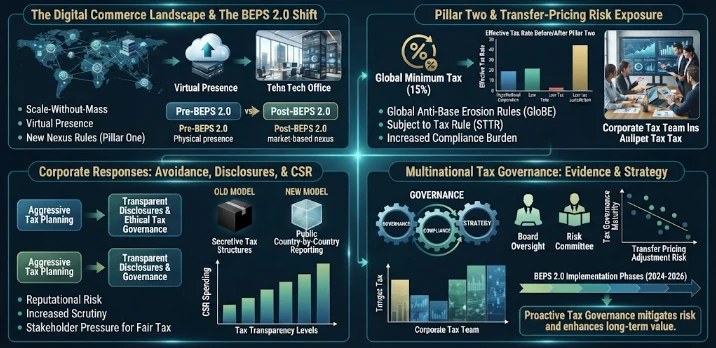
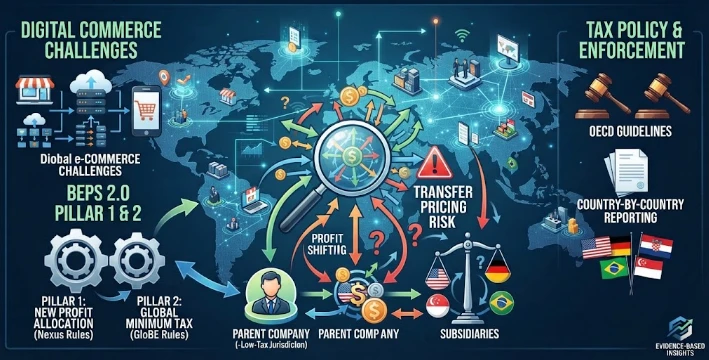
This article examines multinational tax risk where digital business, transfer pricing and accounting governance intersect. Cross-border groups can coordinate sales, intellectual property, financing, data and operational functions across several entities, making it difficult to distinguish commercially defensible profit allocation from strategies designed mainly to shift income into lower-tax jurisdictions. The discussion links BEPS reforms with internal governance, showing why boards and audit c
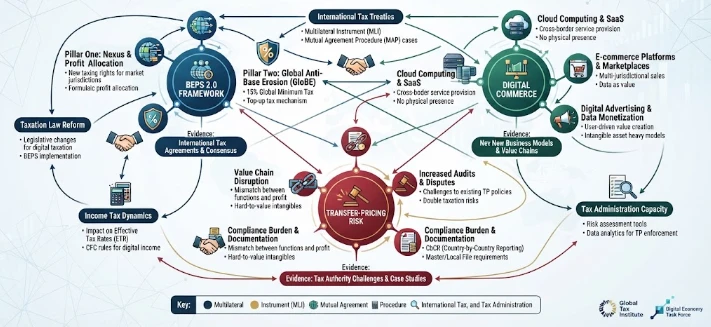
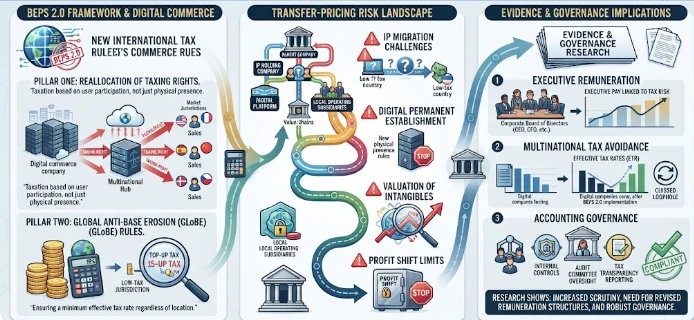
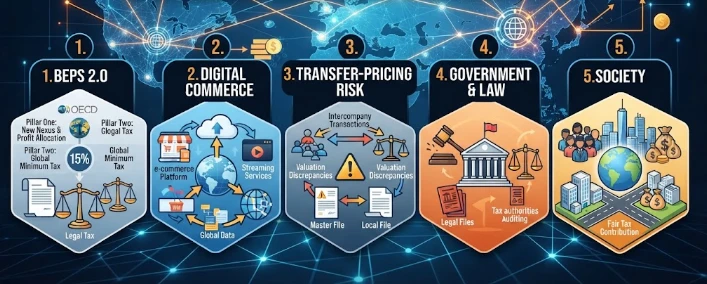
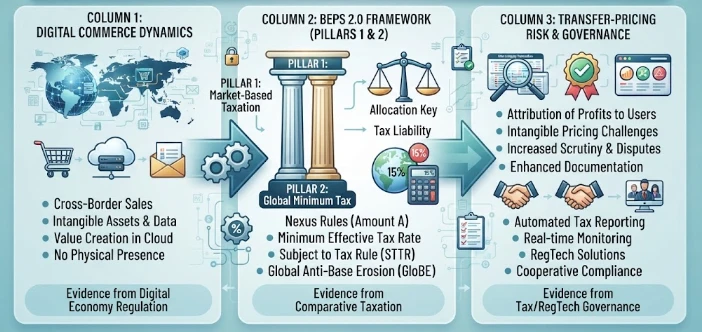
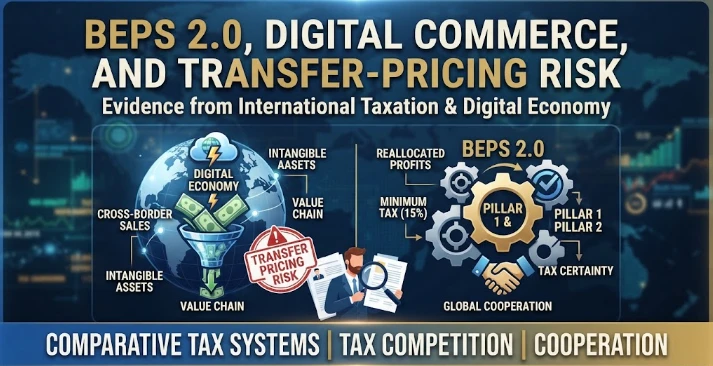
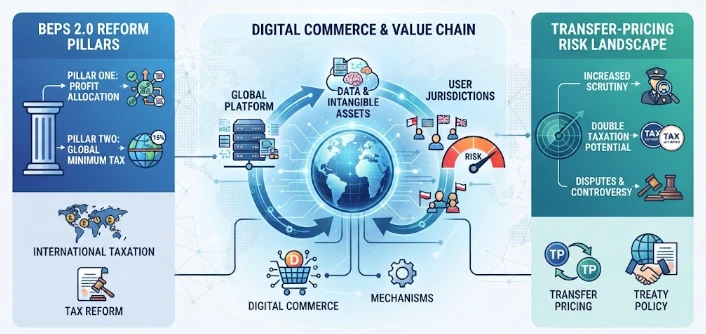
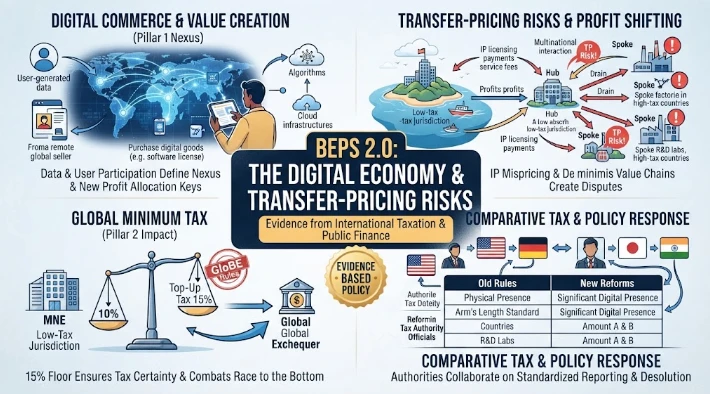
This article examines international tax risk created by digital commerce, transfer pricing and the expanding administrative demands of BEPS 2.0. Multinational groups can distribute sales, intellectual property, financing, data, marketing and operating functions across jurisdictions while legal entities report separate taxable results. That makes the alignment of profit with economic activity a central issue. The article explains that Pillar Two changes the value of some low-tax incentives throug
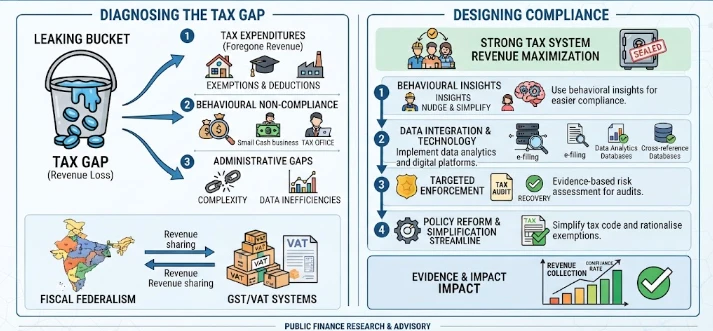
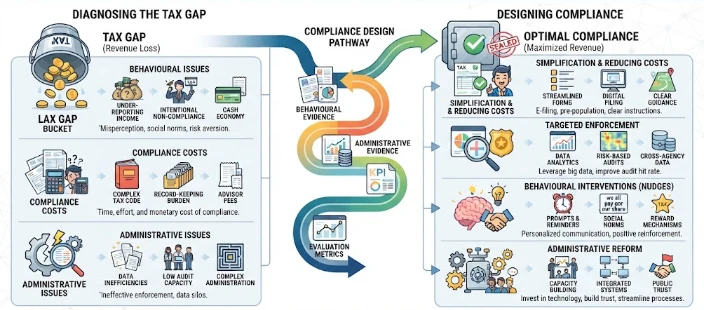
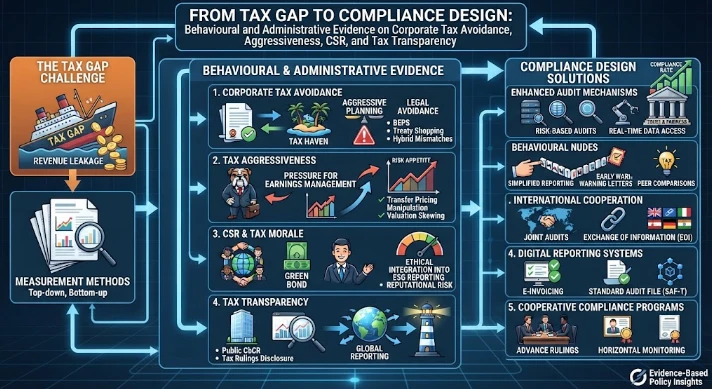
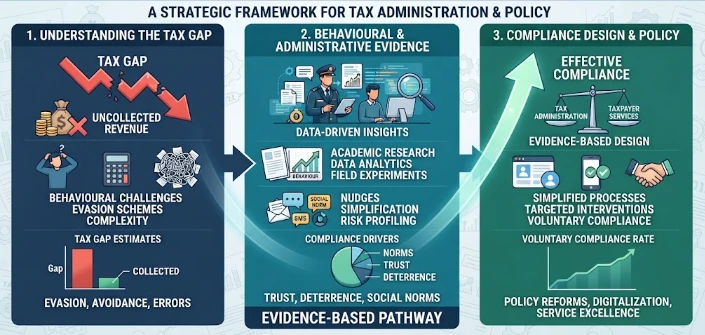
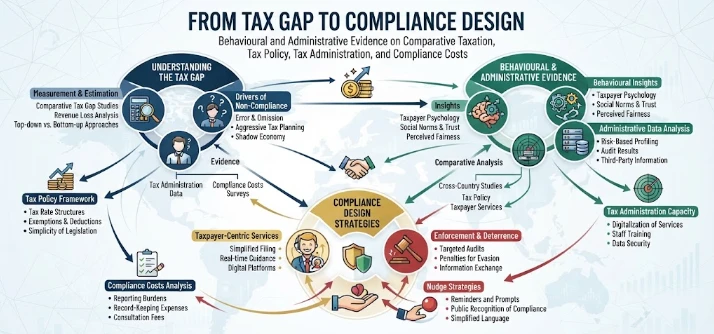
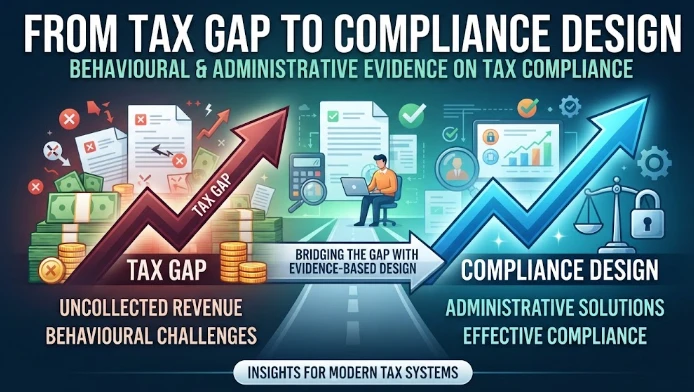
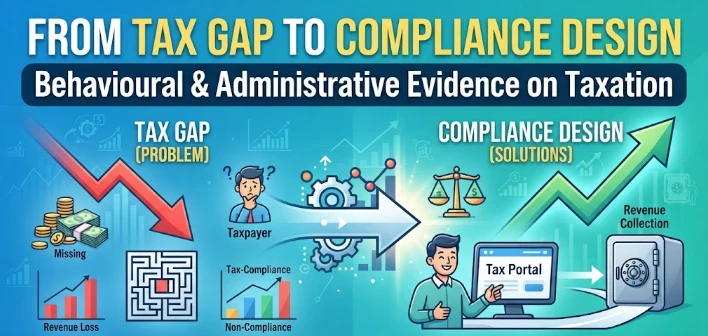
This article treats the tax gap as a diagnostic tool for designing better compliance systems rather than simply a measure of lost revenue. It explains that different gaps require different responses and that fiscal federalism can complicate compliance when several governments share tax bases, definitions, data systems or administrative responsibilities. GST and VAT illustrate how transaction trails, e-invoicing and data matching can strengthen verification, while still creating risks involving r
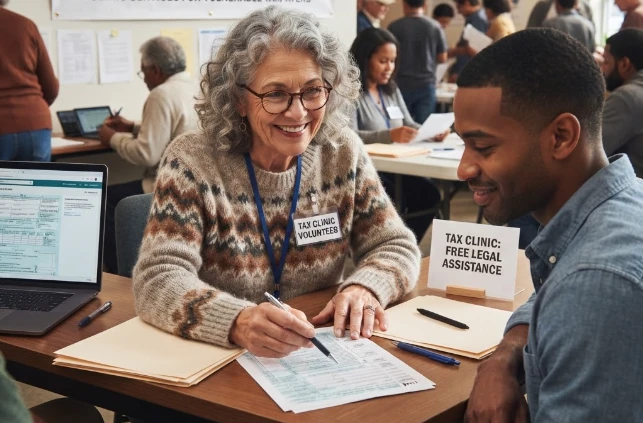
This article explores how tax clinics connect accounting education with practical taxpayer support. It argues that classroom tax problems are usually structured, while real clients may arrive with missing records, unresolved debts, uncertain business classifications or several years of unfiled obligations. The Australian National Tax Clinic model places students under professional supervision so they can apply tax law, accounting, interviewing, research and ethical judgment in real cases. The ar
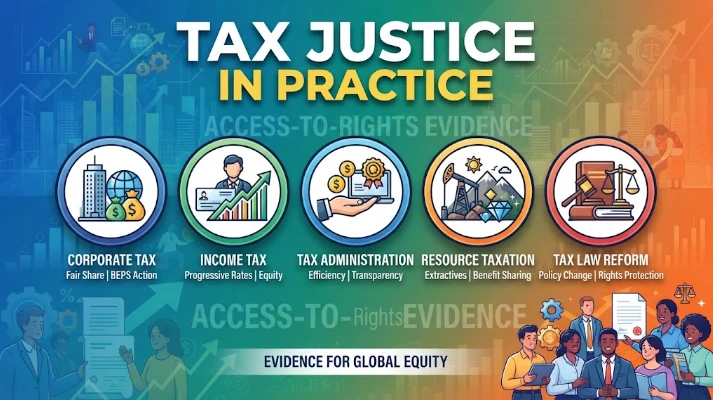
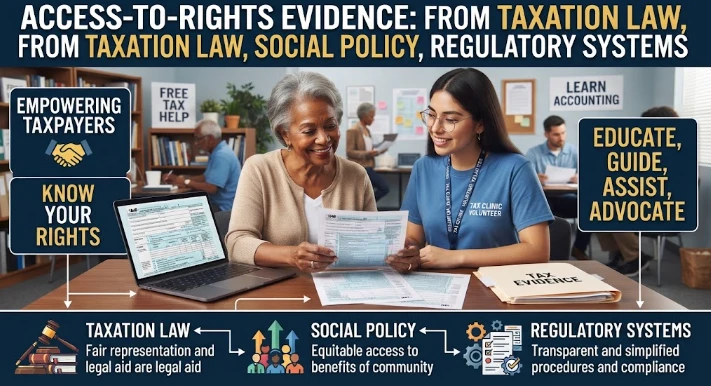
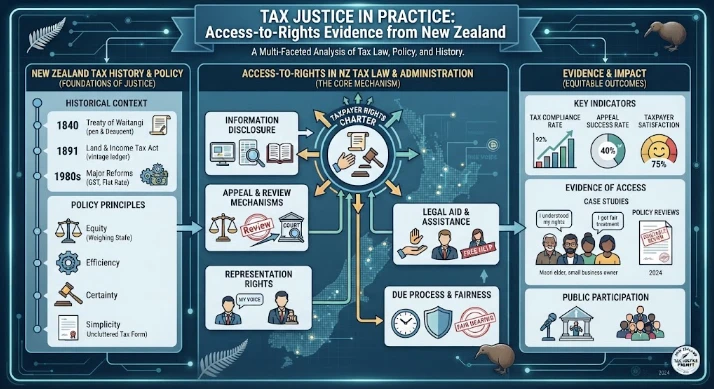
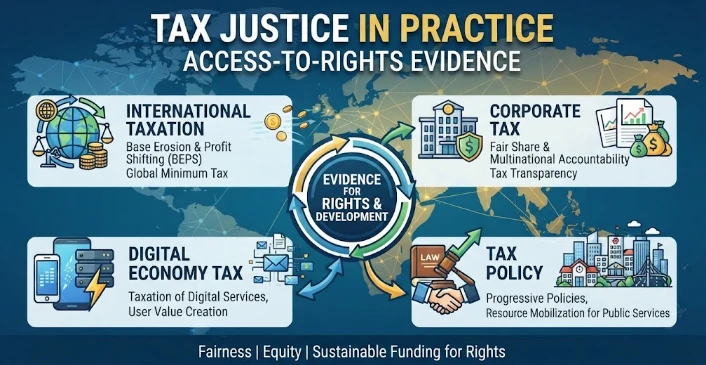
This article examines tax justice across corporate tax, income tax, resource taxation, tax administration and law reform. It begins with procedural access: taxpayers need to understand obligations, obtain records, communicate with authorities, challenge assessments and obtain review without disproportionate cost. Resource taxation adds a distinct public-value question because royalties, rent taxes, company income tax, deductions and project losses interact over long investment cycles. Fairness t
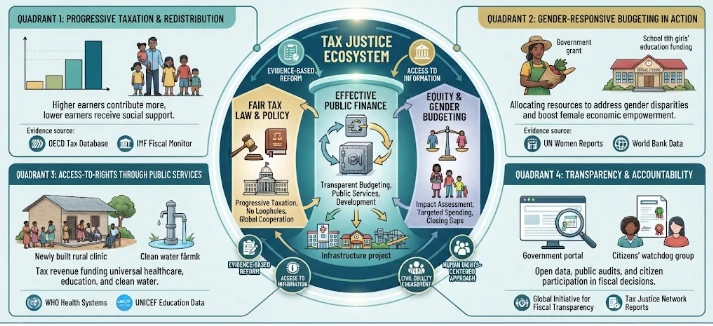
The article presents tax justice as a practical question of whether taxpayers can understand obligations, access records, challenge decisions and obtain review without disproportionate cost. It extends this access-to-rights framework through gender budgeting, public finance and tax reform. Formally neutral thresholds, credits, consumption taxes, childcare rules and retirement concessions can affect groups differently because paid work, unpaid care, savings, property ownership and household struc
This article uses Australian income-tax reform to show why tax justice cannot be judged from headline rates alone. Access to rights requires taxpayers to understand obligations, obtain records, communicate with authorities, challenge assessments and obtain review without excessive cost. The article then considers the revised personal income-tax schedule that took effect on 1 July 2024, emphasizing that thresholds, offsets, family circumstances, inflation, superannuation, capital income and trans
The article moves from tax-gap measurement to practical compliance design, emphasizing that administration must distinguish between error, temporary payment difficulty and deliberate concealment. Compliance costs are especially important for small firms because record keeping, filing, GST reconciliation and digital obligations consume a larger share of limited managerial resources. Transaction trails in GST and VAT can support verification through invoices, e-invoicing and data matching, but lar
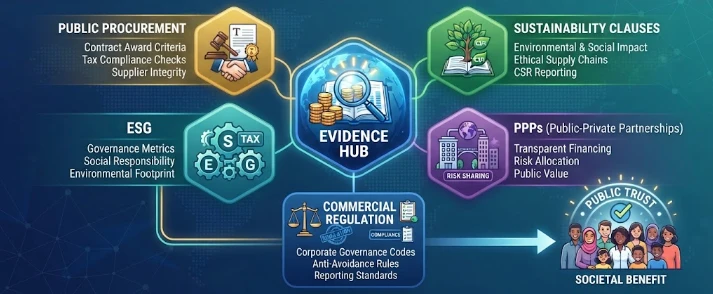
This article links tax transparency with public procurement, sustainability clauses, ESG, public-private partnerships and commercial regulation. Governments purchase infrastructure, health services, technology, transport and everyday goods, so procurement rules can influence environmental performance, labour standards, integrity and innovation. Sustainability requirements are useful only when they are tied to measurable contract performance; vague clauses can become symbolic barriers or reduce c
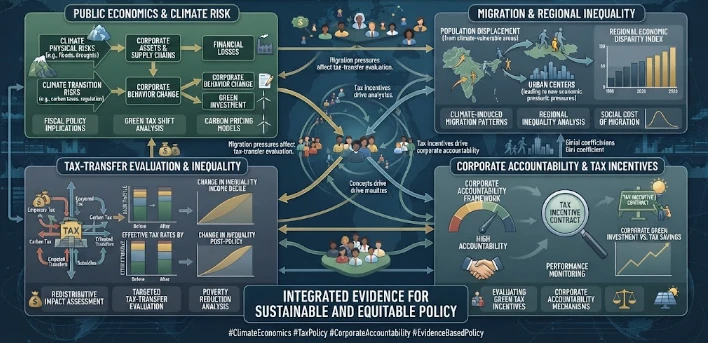
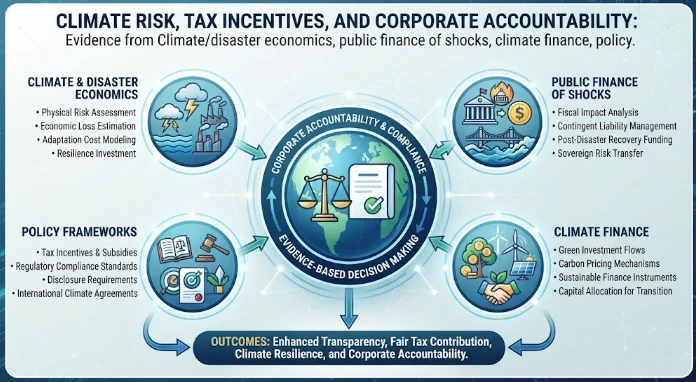
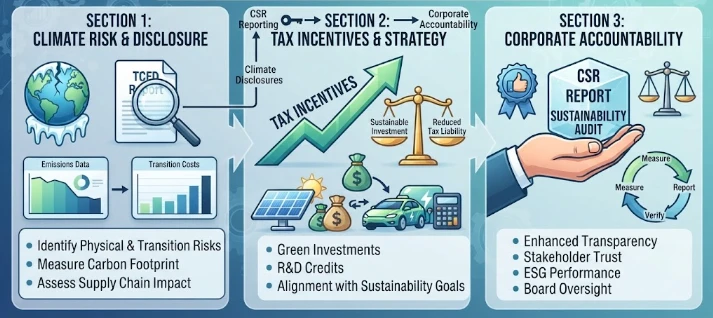
This article examines climate risk, tax incentives and corporate accountability through public economics, inequality, migration and tax-transfer evaluation. It begins from the idea that climate policy is distributional because carbon pricing, clean-investment incentives, rebates, energy subsidies, disaster relief and adaptation spending shift resources across households, firms, places and generations. Lower-income households may face higher relative energy burdens and have less ability to invest
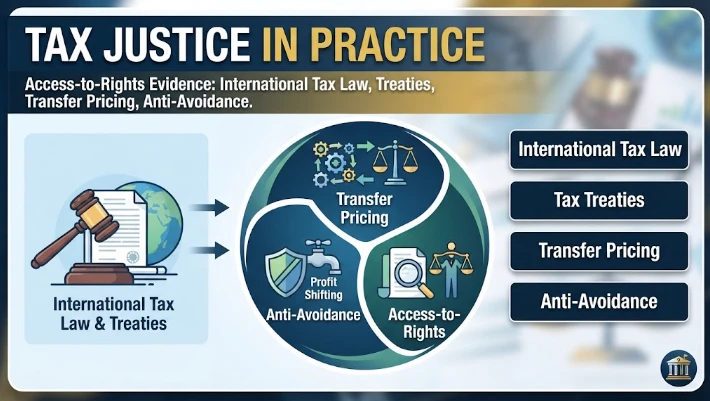
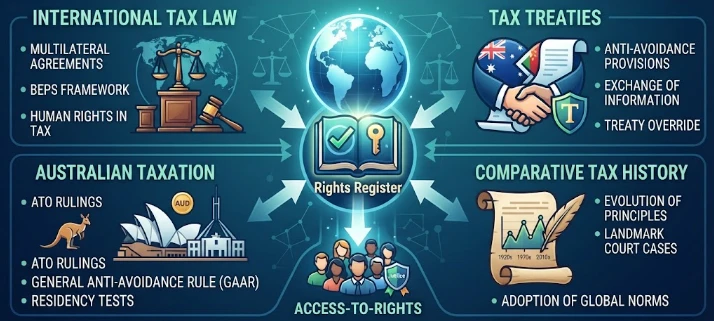
This article applies an access-to-rights framework to international tax law, treaties, transfer pricing and anti-avoidance rules. Cross-border taxation must protect the revenue base without treating every international arrangement as abusive. Treaties reduce double taxation and allocate taxing rights, but structures with limited economic substance can also exploit mismatches. Anti-treaty-shopping provisions, beneficial-ownership concepts, transfer-pricing rules and domestic anti-avoidance measur
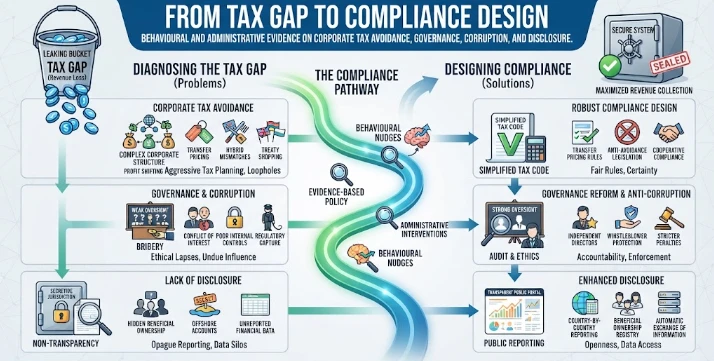
This article reframes the tax gap as a diagnostic tool for designing stronger corporate compliance systems rather than simply a measure of missing revenue. It distinguishes between ordinary tax planning, aggressive arrangements and illegal evasion, arguing that administrations need risk-based methods capable of identifying the transactions and behaviours most likely to create material shortfalls. Large-business assurance programmes, country-by-country reporting, financial statements and related-
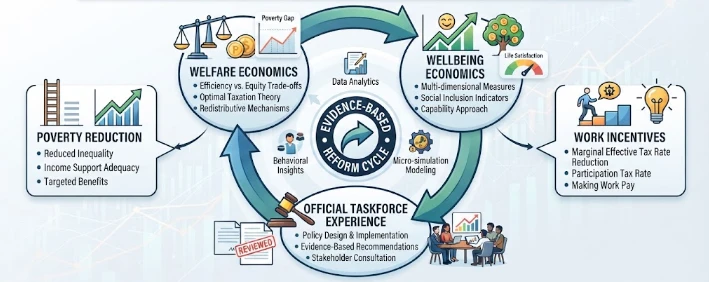
This article evaluates tax-transfer reform through wellbeing economics and welfare economics rather than treating higher employment or disposable income as sufficient measures of success. Household welfare depends on earnings, taxes, benefits and withdrawal rules, but also on housing security, health, education, time, safety, transport and childcare. The article argues that reforms can produce a financial gain while leaving families no better off if essential costs rise or access to services det
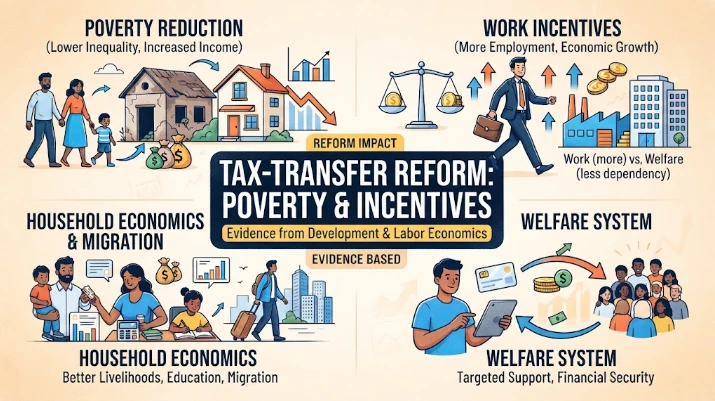
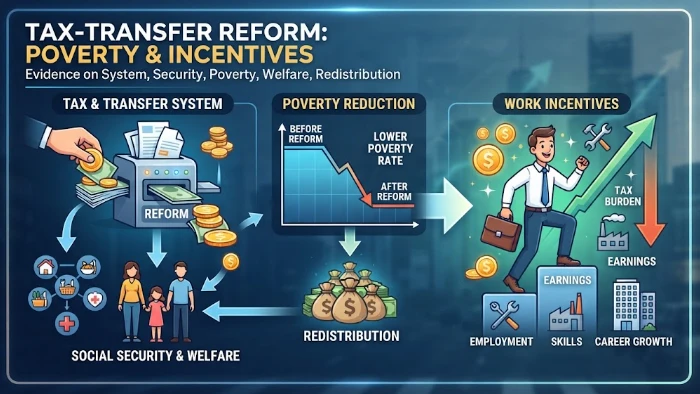
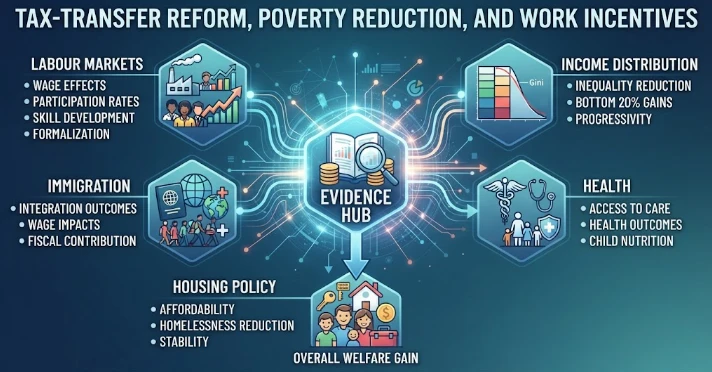
This article examines tax-transfer reform through development economics, labour, welfare, migration and household economics. It argues that policy works through disposable income rather than isolated tax rates, because earnings, taxes, contributions, cash benefits, housing support and withdrawal rules combine in the same household budget. Poverty is treated as more than a temporary income shortfall: health, education, housing, care responsibilities, employment security, migration status and shoc
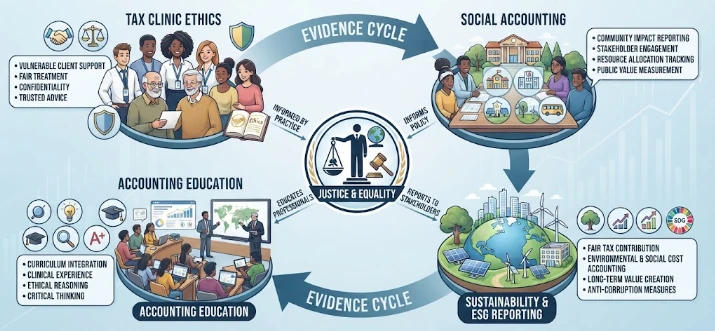
This article approaches tax justice through access to rights, tax-clinic ethics, social accounting and accounting education. It argues that formal rights have limited value when taxpayers cannot understand obligations, collect records, communicate with authorities or obtain affordable review. Tax clinics make these issues visible because clients may arrive with incomplete records, debt, language barriers or fear of enforcement, requiring confidentiality, conflict checks, informed consent and rea
This article treats climate risk as a public-finance and corporate-governance problem shaped by physical hazards, transition policy and fiscal exposure. Floods, heat, storms, droughts and wildfires can reduce revenue while increasing emergency, reconstruction, health and social-protection spending. Disaster economics therefore favours pre-arranged financing through reserves, contingent credit, insurance and risk pools instead of relying only on post-shock improvisation. The article extends this
This article explains why tax administration should distinguish deliberate evasion from error, disputed interpretation and temporary inability to pay. A single tax-gap figure cannot reveal motive, so compliance policy needs diagnostic evidence and proportionate responses. Fiscal federalism can increase complexity when several governments use different definitions, rates, exemptions or data systems, while corporate evasion and avoidance require specialist tools for financing, intangibles, transfe
This article focuses on small-business taxation as a meeting point between public economics and compliance design. Tax-gap estimates identify where legally due revenue is not collected, but they do not reveal whether the cause is poor records, misunderstanding, cash-flow stress, informality or deliberate concealment. Small firms face distinctive pressures because registration, filing, bookkeeping and digital requirements impose fixed costs that consume a larger share of managerial resources. Thr
The article examines corporate tax avoidance through the combined lenses of tax-gap measurement, governance, corruption and disclosure. A tax gap identifies the difference between legal liability and estimated collections, but the policy response depends on what causes the shortfall. Behavioural evidence shows that compliance reflects clarity, trust, fairness, cash-flow pressures and administrative burden as well as sanctions. Governance and corruption matter because selective enforcement, opaqu
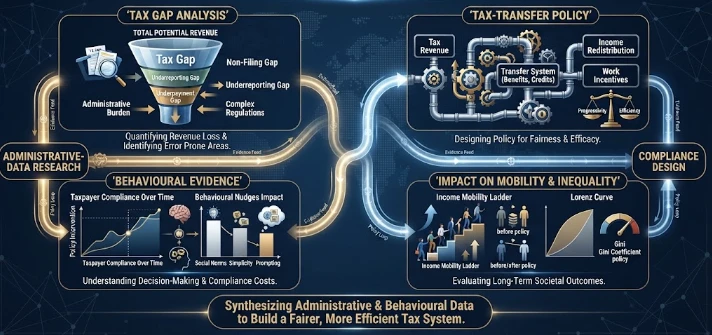
This article connects tax-gap analysis with inequality, income mobility, tax-transfer policy and administrative data. It argues that non-compliance has distributional consequences because the identity of those who underpay matters for the progressivity and legitimacy of the tax system. Deliberate evasion, aggressive avoidance, administrative error, cash-flow problems and exclusion from filing systems should therefore be distinguished rather than treated as one behaviour. Administrative data can
This article explores how executive remuneration and accounting governance shape multinational tax risk in the BEPS 2.0 environment. Digital commerce allows sales, intellectual property, financing, data and management functions to be distributed across jurisdictions, leaving transfer pricing central to the question of where profit should be taxed. Short-term compensation tied closely to after-tax earnings, cash flow or earnings per share may create pressure for aggressive tax planning when gover
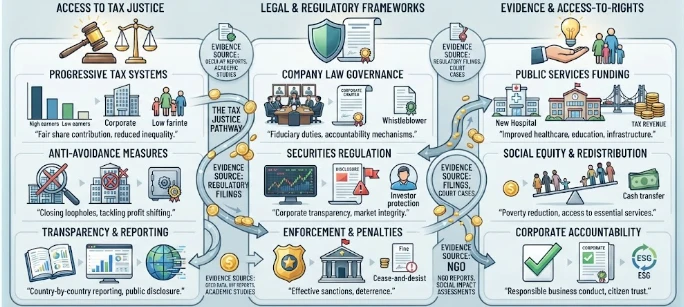
This article extends tax justice beyond rates and redistribution to the practical ability to use legal rights in complex tax systems. Taxpayers need understandable obligations, access to records, communication with authorities, affordable review and predictable procedures. Advanced taxation also intersects with company law and securities regulation because boards, investors, auditors and regulators rely on disclosures concerning tax risk, related-party transactions, deferred tax and uncertain po
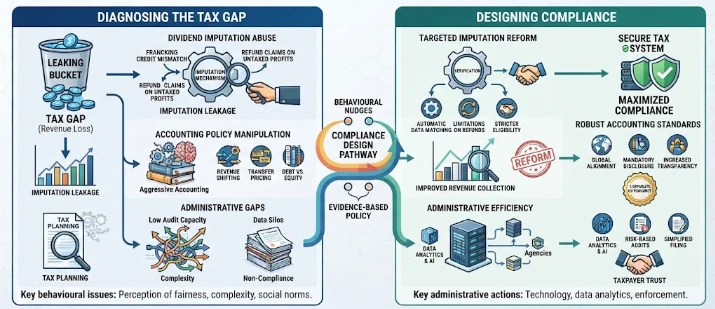
The article connects tax-gap analysis with dividend imputation, accounting policy and corporate tax avoidance. Dividend imputation reduces double taxation of distributed company profits by recognising company tax through shareholder credits, but it also creates integrity questions around franking accounts, eligibility, streaming and refunds. Good compliance design must protect the system without turning ordinary dividend payments into an unnecessarily complex process. The article stresses the im
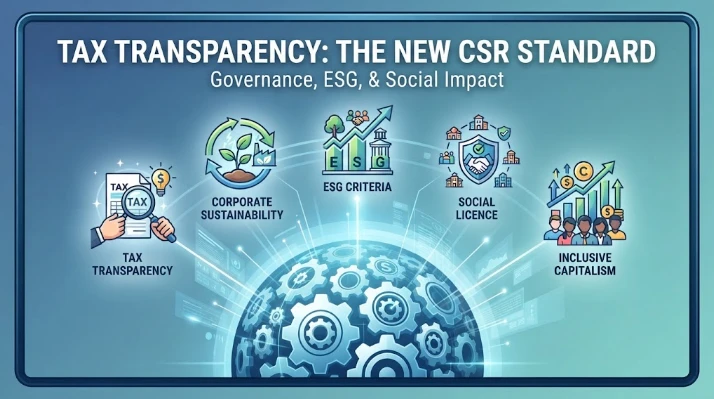
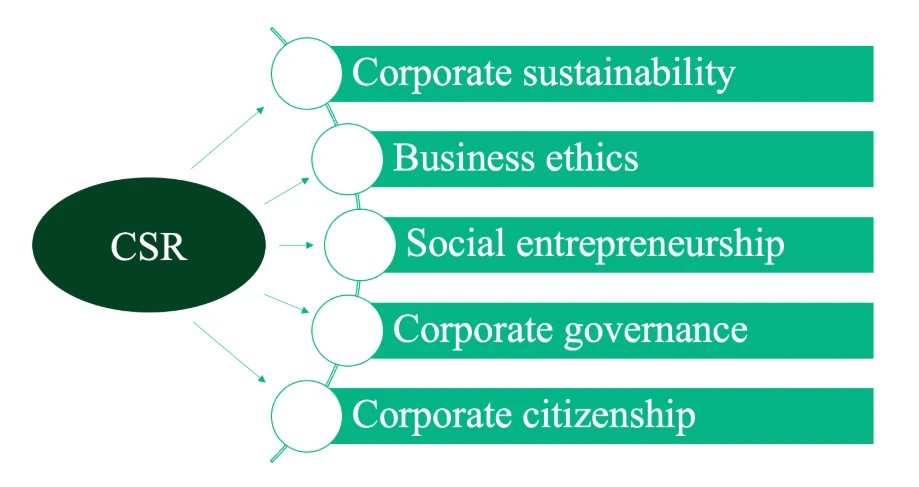
This article examines tax transparency as corporate social responsibility in an environment of mandatory sustainability reporting. It argues that tax strategy should be interpreted alongside governance, public support, stakeholder impact and corporate disclosures rather than reduced to a single effective-tax-rate figure. The discussion highlights the Corporate Sustainability Reporting Directive and European Sustainability Reporting Standards as part of the shift from voluntary sustainability nar
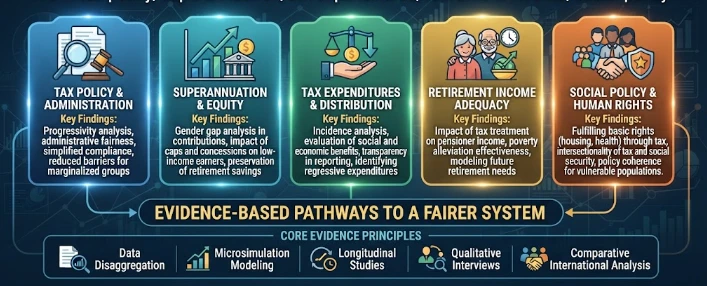
The article examines tax justice through superannuation, retirement-income policy and the distribution of tax expenditures. Retirement concessions are intended to encourage long-term saving, but their value varies widely because higher-income individuals generally have more capacity to contribute and benefit from tax-preferred accounts. Lower-income workers, people with interrupted employment and households facing housing costs may receive much less from contribution-based concessions. The artic
This article uses comparative taxation to show why tax-gap reduction depends on administrative design as much as statutory rules. Similar policy goals can generate very different compliance costs depending on thresholds, registration frequency, exemptions, record requirements, digital systems and dispute procedures. A low tax rate is therefore not necessarily a simple tax system. The article distinguishes simple errors and payment stress from deliberate concealment, supporting risk segmentation
This article examines the relationship between tax law, social policy and regulatory systems, arguing that households experience these systems together even when governments administer them separately. Different definitions of income, reporting periods and eligibility rules can create uncertainty when taxes, social benefits, housing support, employment regulation and business obligations interact. Timing is especially important for workers with variable hours, bonuses, casual jobs or self-employ
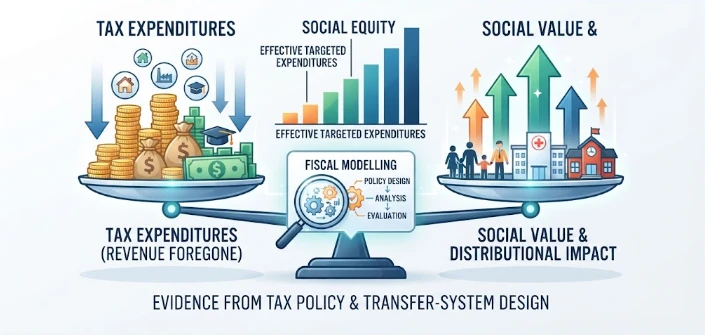
This article asks whether tax expenditures create social value when compared with direct transfers and other uses of public funds. It explains that deductions, exemptions, credits, reduced rates and special allowances are forms of fiscal intervention because they reduce revenue relative to a benchmark tax system. Distribution is central: deductions can be worth more to higher-rate taxpayers, while non-refundable credits may provide little help to households with low tax liabilities. Consumption-
This article reviews New Zealand tax history and policy through the long-standing idea of a broad-base, low-rate system. It traces major reforms from the 1980s, including the introduction of GST, and explains how simplicity, neutrality, efficiency and revenue adequacy have remained important design principles. At the same time, the article shows that those principles are repeatedly tested by debates over capital gains, housing, distribution, Māori interests, digital commerce and international ta
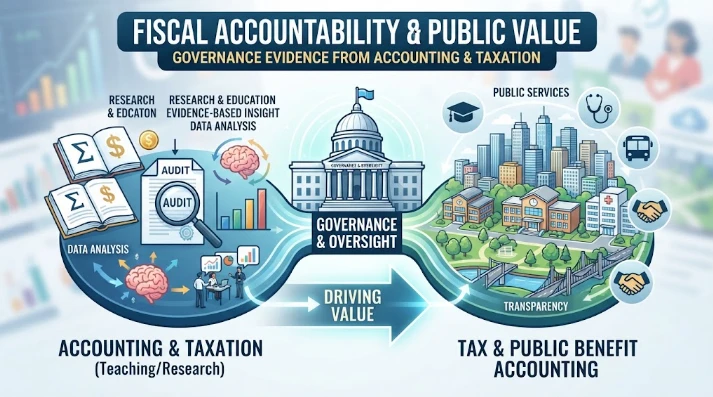
The article connects fiscal accountability with accounting, taxation teaching, research and public-benefit reporting. It begins from the idea that every tax collected, concession granted or public resource used should be linked to an identifiable public purpose and assessed against outcomes. Fiscal transparency requires more than budget totals because forecasts can differ from actual collections as economic growth, prices, behaviour, litigation and policy take-up change. Tax-gap analysis and mic
This article places BEPS 2.0 within a broader relationship between taxation law, government capacity, markets and society. Digital commerce allows revenue, data, intellectual property, financing and marketing functions to be distributed across jurisdictions, making transfer pricing and the location of taxable profit difficult to establish. Governments need revenue for public services, while businesses need certainty and protection from double taxation; the article presents international tax refo
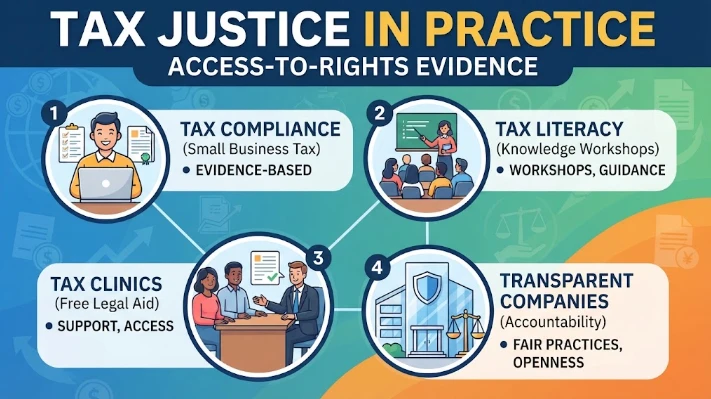
The article links tax justice with compliance, tax literacy, tax clinics, corporate transparency and the practical difficulties faced by small businesses. Access to rights requires more than formal legal equality: taxpayers must understand obligations, obtain records, communicate with authorities, challenge assessments and secure review without excessive cost. Tax clinics provide a direct response for individuals and small firms that cannot easily obtain professional advice, while recurring case
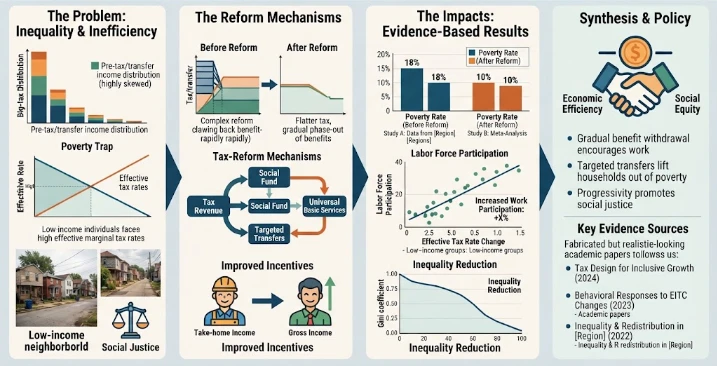
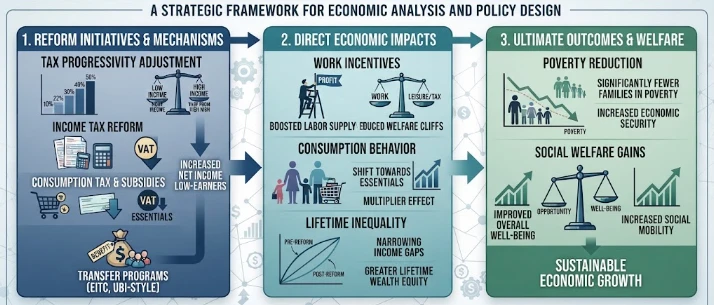
This article analyses tax-transfer reform through behavioural responses, inequality and social justice. It explains that redistribution affects work, saving, investment, consumption, business structure and compliance, so reform should be assessed through the total effect on disposable household income rather than a single tax rate. Labour-supply incentives are highlighted through participation tax rates and effective marginal tax rates, which can become high when taxes rise at the same time that
This article explains how microsimulation can make tax-transfer reform visible at the household level. Disposable income is determined by earnings, income tax, social contributions, cash benefits, housing support, family payments and withdrawal rules, so a change in one instrument may produce a much smaller net gain after other rules respond. Using representative microdata, models such as New Zealand Treasury’s TAWA framework can compare policy packages across income groups, household types and
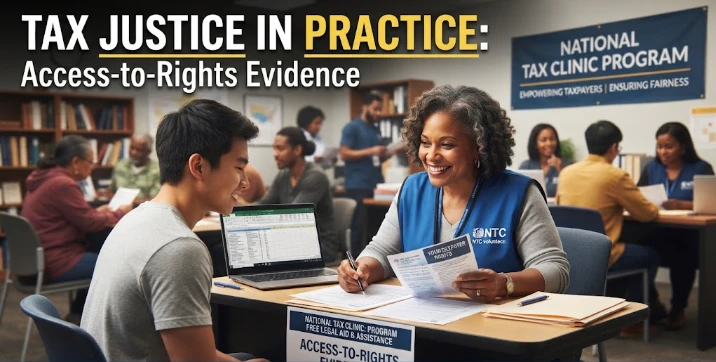
This article examines Australia’s National Tax Clinic programme as a model that combines taxpayer assistance, professional education and institutional learning. It argues that tax compliance depends not only on legislation and enforcement but also on whether taxpayers can understand rules, assemble records, respond to notices and obtain help when problems arise. Clinics provide free assistance to eligible individuals and small businesses and can address overdue lodgements, tax debt, payment arra
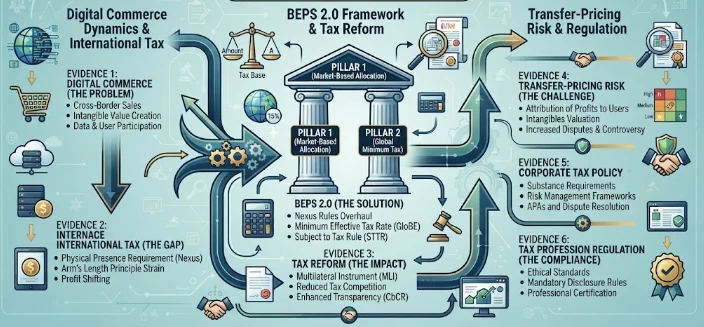
This article examines BEPS 2.0, digital commerce and transfer-pricing risk through the lens of multinational tax governance and corporate responsibility. It explains how global groups can separate legal entities, intellectual property, financing, data and management across jurisdictions, creating opportunities for profit shifting and complexity in determining where value is created. The article outlines the two-pillar international tax framework, with Pillar One addressing nexus and profit alloc
This article uses international tax law, Australian taxation and comparative tax history to frame tax justice as access to usable rights. Formal protections are insufficient if taxpayers cannot understand obligations, obtain records, challenge assessments or secure review without disproportionate expense. Australia’s international tax rules sit on a long domestic history of income taxation, corporate taxation, anti-avoidance measures and treaty development, showing that concepts such as residenc
This article shows how income-tax non-compliance often begins in accounting records before a tax return is filed. Missing invoices, mixed personal and business expenses, weak payroll records and inconsistent classifications can later appear as under-reported income or overstated deductions. Compliance design should therefore address bookkeeping quality and regulatory behaviour upstream rather than relying only on post-filing enforcement. The article also discusses how tax expenditures and specia
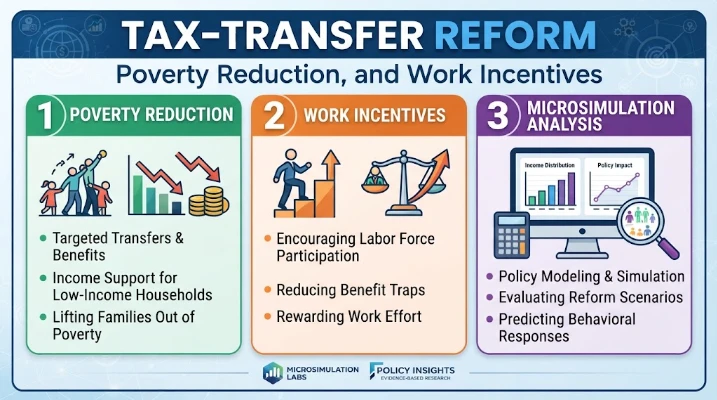
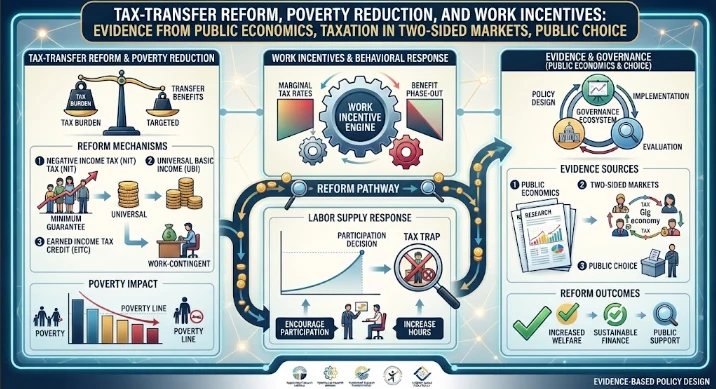
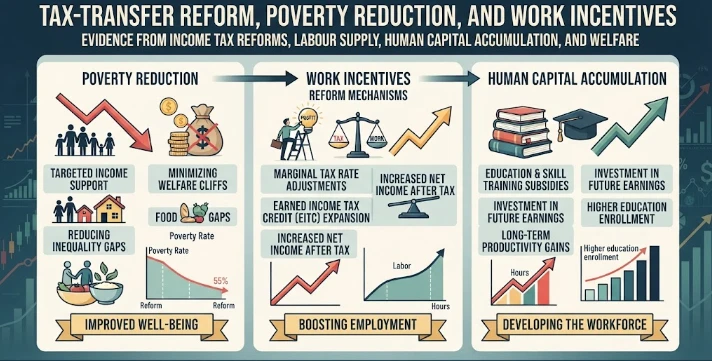
This article examines how tax-transfer systems can reduce poverty while preserving clear incentives to work and progress in employment. It focuses on the interaction of income tax, social contributions, cash benefits, housing support, family payments and in-work credits in shaping household disposable income. The discussion highlights effective marginal tax rates and benefit-withdrawal cliffs, showing how several programmes can combine to make extra earnings produce only a small net gain. Househ
The article examines tax-transfer reform through disposable income, economic welfare, poverty, mobility and household-level modelling. It argues that the relevant policy object is the complete household budget after income tax, social contributions, cash benefits, housing support, family payments and benefit withdrawal, rather than any single statutory rate. Mobility adds a dynamic dimension because temporary low income after job loss or study differs from persistent disadvantage that may requir
This article examines BEPS 2.0 through comparative taxation, digital-economy regulation and tax/regtech governance. Digital businesses can separate sales, intellectual property, financing, data, marketing and operational functions across jurisdictions, making transfer pricing and the location of value creation difficult to assess. Different countries respond through corporate tax rules, treaty reform, digital levies, platform reporting, withholding systems and transaction-level data, creating co
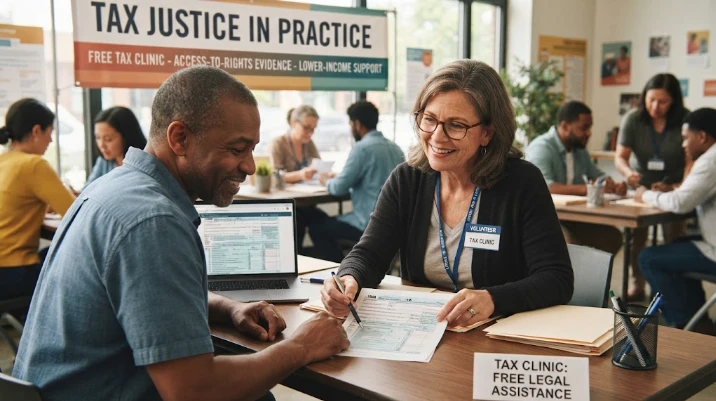
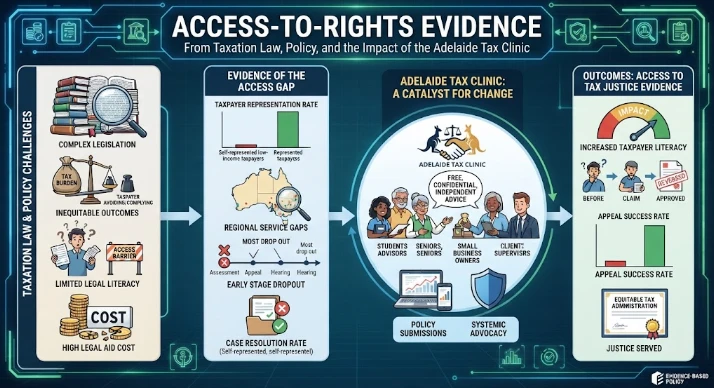
This article examines tax clinics as institutions that convert formal taxpayer rights into practical access to justice for lower-income individuals and small businesses. Using the Australian National Tax Clinic model, it shows how supervised university clinics provide free assistance with returns, debt, penalties, registrations, business obligations and disputes. The article stresses that tax vulnerability can accumulate over time through missed filings, weak records, cash-flow problems, digital
This article applies public economics, two-sided-market analysis and public-choice theory to tax-transfer reform. It begins from the household budget constraint, where earnings, taxes, contributions, cash benefits, housing support and family payments jointly determine disposable income. Two-sided markets complicate tax incidence because a levy imposed on one group can change prices, commissions or service quality for another group, meaning legal liability does not necessarily identify the final
This article evaluates tax expenditures as public interventions whose social value should be tested as carefully as direct government spending. It explains that deductions, exemptions, credits and preferential rules are measured against a benchmark tax system, so the choice of counterfactual shapes the apparent fiscal cost. Distributional analysis is essential because deductions may be worth more to higher-rate taxpayers, while non-refundable credits can provide little immediate support to house
This article uses the Adelaide tax-clinic model to illustrate how access to professional assistance can make taxpayer rights meaningful in practice. It explains that the Australian National Tax Clinic network was created to assist individuals and small businesses who lack the resources to obtain conventional tax advice. The Adelaide clinic demonstrates that tax assistance often extends well beyond current-year returns to overdue lodgements, debt, payment arrangements, registrations, disputes, pe
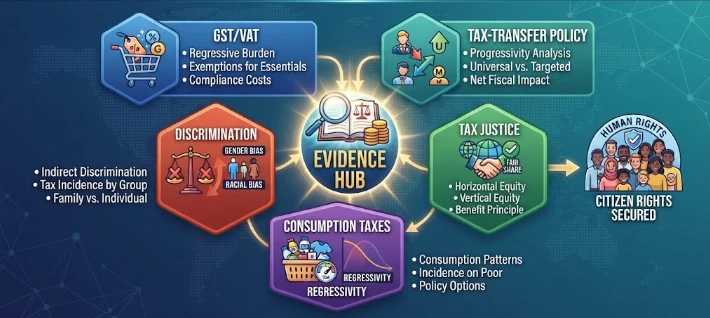
This article examines tax justice through GST, VAT, consumption taxes, tax-transfer policy and discrimination. Broad consumption taxes can raise revenue efficiently, but lower-income households may spend a larger share of current income, creating distributional concerns. Reduced rates for essentials can provide relief but also benefit higher-spending households and create additional classification complexity. Targeted transfers may compensate more precisely when administrative systems can reliab
The article examines income-tax reform through labour supply, welfare and human-capital accumulation rather than assuming that lower tax rates automatically increase work. Average tax rates affect disposable income, while marginal rates influence the reward from additional hours or higher-paying employment, and these effects can operate in different directions. Benefit withdrawal is equally important: gradual tapers can smooth transitions into work, while abrupt thresholds may create cliffs that
This article links climate risk, tax incentives and corporate accountability through sustainability reporting and climate-related disclosure. Physical hazards and transition policies can affect asset values, supply chains, insurance, operating costs and public budgets, while tax systems influence the transition through carbon pricing, investment allowances, accelerated depreciation and targeted credits. The article highlights IFRS S1 and IFRS S2 as frameworks that connect governance, strategy, r
This article examines digital commerce and BEPS 2.0 through comparative taxation, tax competition and international cooperation. It explains that digital businesses can create value through customers, data, intellectual property and remote services across multiple jurisdictions, while tax systems remain nationally based. The original BEPS programme addressed treaty abuse, transfer pricing, interest deductions, hybrid mismatches and country-by-country reporting, while the two-pillar framework add
This article presents tax transparency as part of corporate governance, sustainability, ESG, social licence and inclusive capitalism. Investors, employees, customers, governments and communities increasingly assess tax strategy alongside claims about responsible business, making context more useful than a single effective-tax-rate figure. The article links sustainability to board decision rights, incentives, oversight and accountability, noting that reporting frameworks have moved sustainability
This article treats the tax gap as a diagnostic tool linking taxation law, revenue law, administration and policy design. Legal rules define liabilities, but actual compliance depends on registration, filing, payment, audit, collection, dispute resolution and the quality of records and third-party information. Using published Australian GST-gap evidence, the article shows why a gap estimate cannot by itself reveal whether non-compliance results from error, cash-flow difficulty or deliberate conc
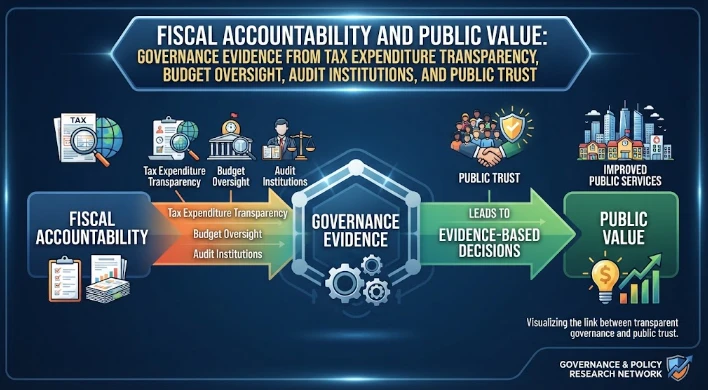
This article links fiscal accountability and public value with tax-expenditure transparency, budget oversight, audit institutions and public trust. It argues that exemptions, deductions, credits, concessional rates and deferrals can pursue spending-like objectives and should therefore face budget-style scrutiny. Australia’s Tax Expenditures and Insights Statement is used to illustrate how revenue-forgone estimates and distributional analysis can make concessions more visible without assuming tha
This article examines BEPS 2.0 through international taxation, transfer pricing, treaty policy and tax reform. Digital commerce makes it difficult to assign value creation to a single jurisdiction because sales, intellectual property, financing, data and operational functions can be distributed across multinational groups. Transfer pricing therefore remains central, particularly where intangibles and integrated business models make reliable comparables difficult. The article discusses simplified
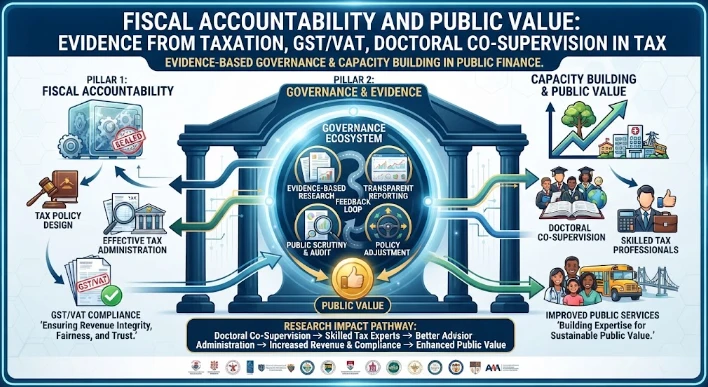
The article frames fiscal accountability around a basic public-value question: what outcomes result from each unit of revenue collected, forgone or spent? It links taxation, GST and VAT administration with governance, professional education and doctoral research. Cross-disciplinary tax research can combine legal doctrine, administrative data, public finance and taxpayer behaviour to test whether rules are coherent, administrable and equitable. The article also argues that tax education should in
The article argues that tax progressivity should be assessed across the entire fiscal system and over time, not from one annual tax table. Income changes through education, career progression, unemployment, family formation and retirement, so annual inequality can differ substantially from lifetime inequality. Consumption also matters because lower-income households often spend a larger share of current income, making broad consumption taxes appear regressive even when they are administratively
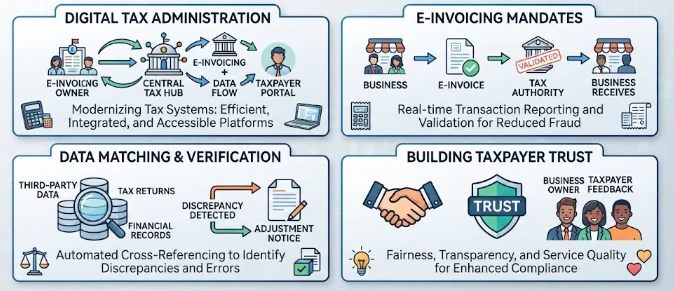
This article examines how digital tax administration, e-invoicing and data matching can move compliance closer to the transactions that create tax liabilities. Tax-gap estimates remain diagnostic rather than proof of motive, so administrations need to distinguish simple error, payment difficulty and deliberate concealment. The article highlights electronic filing, digital identity, APIs and structured invoice data as tools for bookkeeping, pre-filling, VAT control and risk assessment. These syst
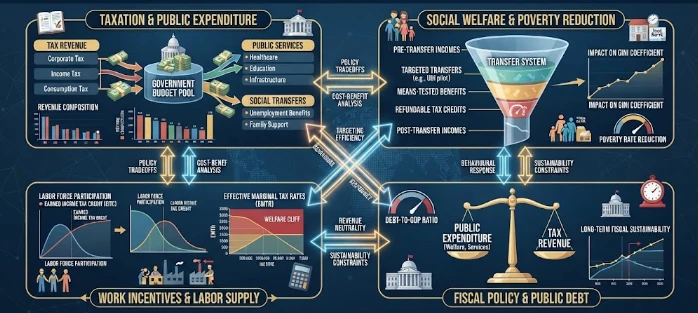
This article presents tax-transfer reform as an integrated public-finance problem involving taxation, public expenditure, social welfare and public debt. Governments need revenue for health, education, infrastructure, pensions and debt service while households need protection from poverty and a predictable financial return from work. The article argues that tax policy should therefore be assessed together with spending and transfer policy rather than as separate systems. Work incentives depend o
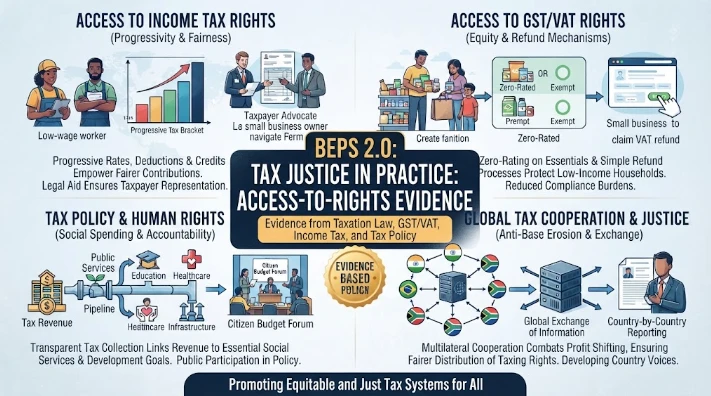
This article examines tax justice through the interaction of GST or VAT, income tax and tax policy. It begins from access to rights, arguing that taxpayers must be able to understand obligations, obtain records, challenge assessments and secure review without disproportionate expense. Consumption taxes illustrate a classic distributional tension: broad bases can provide stable revenue and reduce classification disputes, but lower-income households may spend a larger share of current income on co
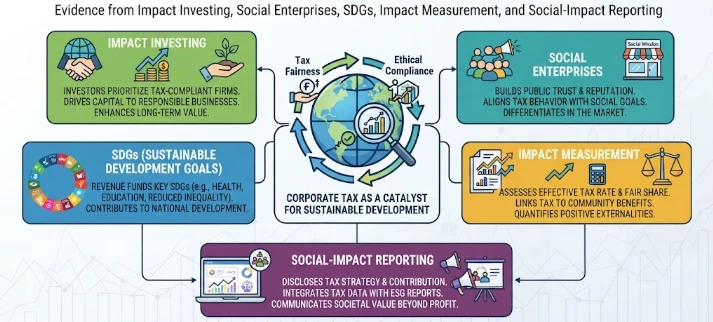
This article connects tax transparency with impact investing, social enterprises, the Sustainable Development Goals and social-impact reporting. It argues that corporate tax responsibility cannot be judged from a single effective tax rate because losses, incentives, grants, cross-border structures and timing differences can materially affect results. For impact investors, the key issue is separating market performance from value created through public fiscal support, including tax concessions an
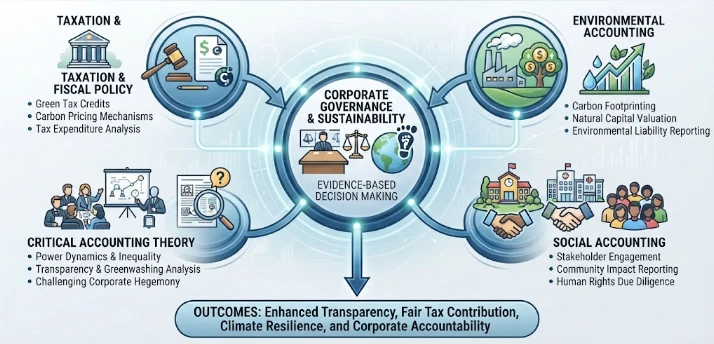
This article connects climate risk with taxation, environmental accounting, social accounting and critical accounting theory. Physical hazards and transition policies can change asset values, operating costs, insurance, supply chains and public budgets, making climate policy a fiscal as well as environmental issue. Tax credits, accelerated depreciation and other incentives can lower the private cost of low-carbon investment, but their public value depends on additional emissions reduction, resil
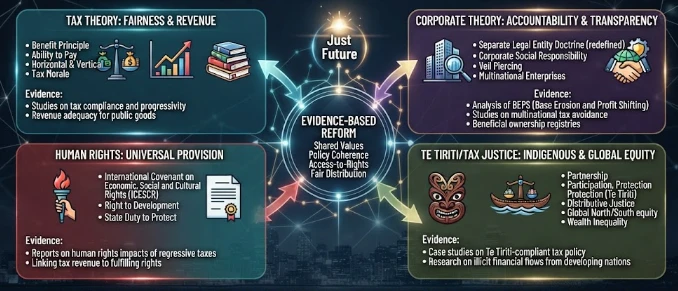
This article approaches tax justice through tax theory, corporate taxation, human rights and Te Tiriti o Waitangi in Aotearoa New Zealand. It argues that fairness cannot be judged only by rates because tax bases, economic incidence, legal structures, public services and historical conditions all shape outcomes. Classical principles such as equity, efficiency, certainty, simplicity and revenue adequacy remain important, but the article shows how they can conflict in practice. Corporate taxation a
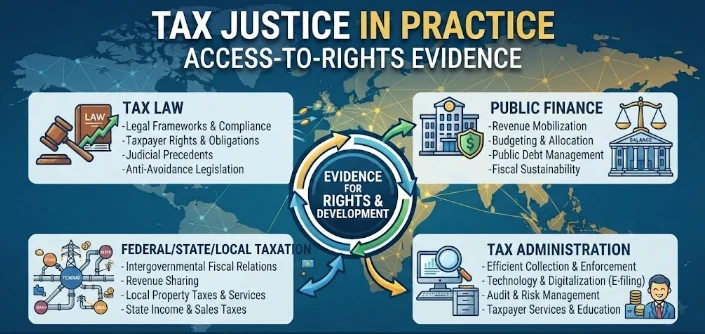
This article examines tax justice across federal, state and local taxation through an access-to-rights lens. It argues that taxpayers encounter government as a connected system even when property taxes, payroll taxes, consumption taxes, income taxes, fees and transfers are administered by different authorities. Differences in bases, filing procedures, review mechanisms and responsibilities can therefore create practical inequality and unnecessary compliance burden. Public finance adds another qu
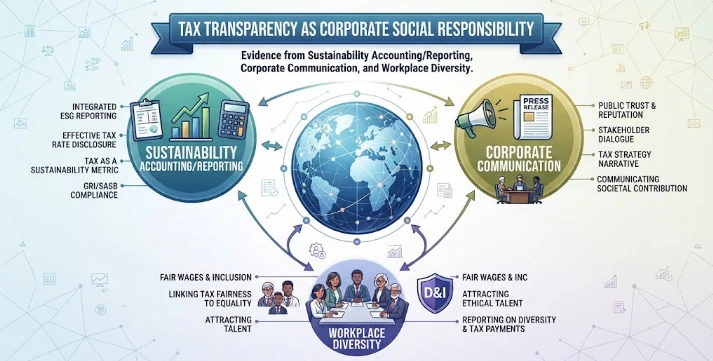
This article examines tax transparency as part of corporate social responsibility, sustainability accounting and corporate communication. It argues that tax strategy should be understood alongside governance, public support and broader economic impact rather than reduced to a single effective-rate comparison. Sustainability reporting increasingly asks organisations to connect narrative commitments with measurable risks, performance and governance processes. Workplace diversity provides a paralle
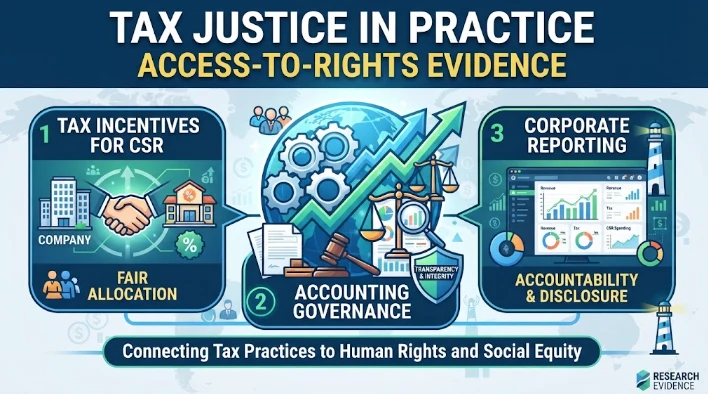
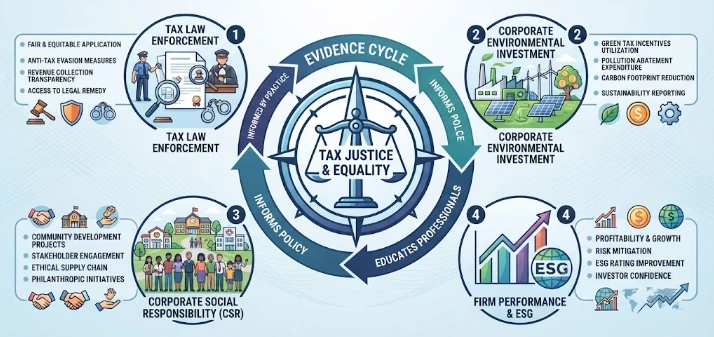
This article evaluates tax incentives for corporate social responsibility as forms of tax expenditure that should be assessed for public value, additionality and governance. Deductions, credits, accelerated allowances and preferential treatment can encourage environmental investment, research, training or community activity, but each concession reduces government revenue compared with a benchmark system. The article argues that a CSR label does not automatically demonstrate social value. Policym
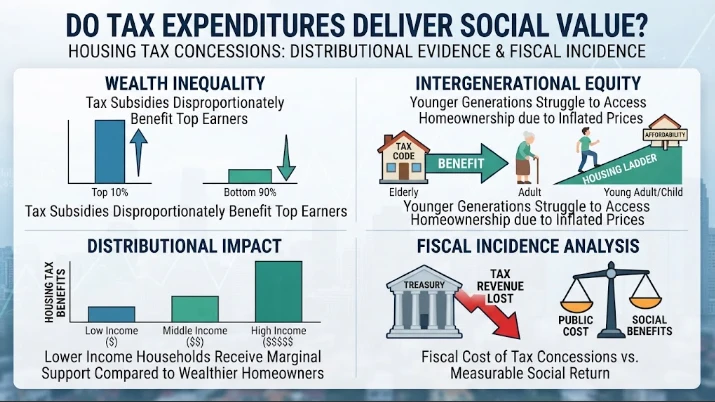
This article assesses the social value of housing tax concessions through wealth inequality, intergenerational equity and fiscal incidence. It argues that household welfare is shaped by the full tax-transfer system, but housing concessions require a wealth lens because benefits depend on asset ownership, leverage, taxable income, capital gains treatment and the tax status of owner-occupied or investment property. Renters and households without assets may benefit less directly, while tax preferen
This article explores how international tax reform has expanded the responsibilities of tax professionals and corporate governance systems. Digital commerce makes value creation difficult to locate, while multinational groups must manage transfer pricing, Pillar Two calculations, country-by-country data, treaty analysis, deferred tax and domestic anti-avoidance rules. Professional advisers can improve compliance and certainty, but the article notes potential conflicts between aggressive planning
This article explains how international corporate taxation is changing in response to digital business models, profit shifting and competition between jurisdictions. It argues that traditional assumptions about business location are increasingly strained when customers, intellectual property, financing and operations are spread across countries. The article reviews the BEPS agenda and the two-pillar reform framework, emphasizing that Pillar Two’s minimum-tax rules change the value of very low ef
This article uses tax clinics to show how fiscal justice depends on the real accessibility of tax law and administration for vulnerable taxpayers. It argues that fairness is not achieved merely because everyone is subject to the same rules; people experiencing low income, unstable work, disability, migration, business failure or digital exclusion may face much greater costs in meeting identical obligations. The Australian National Tax Clinic programme illustrates how professional supervision and
This article broadens tax-transfer reform by linking household income with labour markets, immigration, health and housing policy. Disposable income is shaped by earnings, taxes, social contributions, cash benefits, housing support and benefit withdrawal, but households also face childcare, commuting and local housing costs that can alter the real return from work. Immigration can affect labour supply, labour demand, household composition and settlement patterns, while health influences the capa
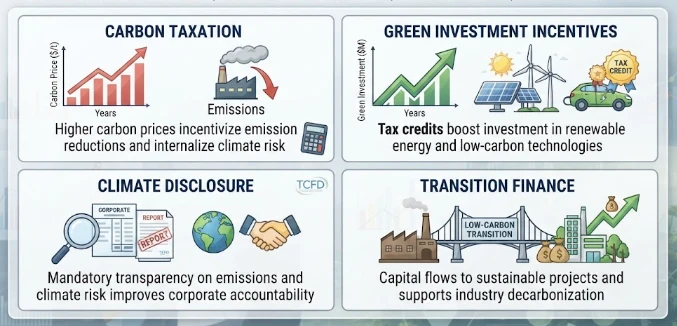
This article compares carbon taxation, green investment incentives, climate disclosure and transition finance as tools for managing climate risk. Carbon pricing raises the cost of emissions across covered activities, while credits and accelerated deductions reduce the cost of specified low-carbon investments. Each instrument can change behaviour, but both may also create windfalls if policy does not test additionality, technology maturity and interaction with existing regulation. The article arg
This article frames international tax justice as a question of usable rights, not only tax rates or redistribution. As digital business expands, taxpayers and smaller entities need clear rules on source, residence, profit allocation, minimum taxation, transfer pricing and dispute procedures when more than one jurisdiction claims taxing rights. The article argues that legal certainty should not depend on expensive specialist advice, so public guidance, safe harbours, published administrative posi
This article examines tax transparency as a component of corporate social responsibility, accounting and public-sector accountability. Financial statements disclose current tax, deferred tax, effective rates and uncertain positions, but those figures do not always correspond directly with cash tax paid in each jurisdiction. The article therefore argues that transparency should provide context for differences caused by losses, depreciation, incentives, timing and group structures. Country-by-coun
This article examines tax justice where enforcement, corporate environmental investment, corporate social responsibility and firm performance intersect. It begins from access to rights, arguing that taxpayers need understandable obligations, affordable review and practical ways to challenge decisions. Environmental tax incentives create an additional enforcement problem because qualifying expenditure and performance must be verified without making legitimate projects unnecessarily difficult to c
This article connects tax transparency with co-produced performance measurement in nonprofit and social-purpose organisations. It argues that tax reporting becomes part of corporate social responsibility when stakeholders need to understand how statutory obligations, incentives, losses and public support relate to wider social outcomes. For nonprofits, effective measurement begins when funders, staff, service providers and affected communities jointly define what success means rather than relyin
This article analyses BEPS 2.0 using international taxation, comparative tax policy and public finance. It argues that the effective burden on multinational activity depends on far more than the statutory corporate tax rate, including tax bases, loss rules, depreciation, withholding taxes, incentives, resource rents, payroll taxes, consumption taxes and administrative enforcement. Countries also differ in how strongly they rely on corporate tax revenue and in their capacity to absorb losses from
This article connects tax-gap analysis with financial reporting, corporate governance and research on tax avoidance. It cautions that book-tax differences are not automatically evidence of aggressive behaviour because accounting profit and taxable income can diverge legitimately through depreciation, losses, tax credits, exempt income, consolidation, foreign operations and timing rules. Financial statements can therefore provide risk signals, but tax administrations need additional evidence befo