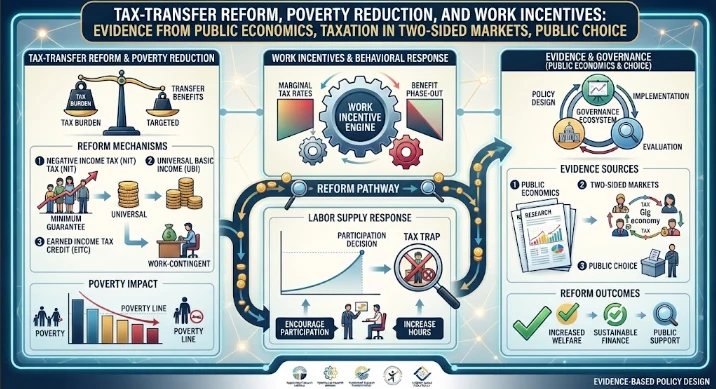
This article applies public economics, two-sided-market analysis and public-choice theory to tax-transfer reform. It begins from the household budget constraint, where earnings, taxes, contributions, cash benefits, housing support and family payments jointly determine disposable income. Two-sided markets complicate tax incidence because a levy imposed on one group can change prices, commissions or service quality for another group, meaning legal liability does not necessarily identify the final economic burden. Microsimulation remains useful for household distribution, but market structure and elasticities are also required. The article discusses targeted support, effective marginal tax rates, gradual benefit tapers, mobility, human capital and broader welfare outcomes beyond employment counts. Public-choice analysis adds a political dimension because narrow concessions may create concentrated benefits while spreading costs across a larger tax base, making weak programmes difficult to reform. Consumption taxes illustrate the tension between efficient revenue collection and distributional pressure on lower-income households. Administrative design, digital access and fiscal sustainability also shape outcomes. Transparent modelling can expose hidden trade-offs before thresholds and incentives become entrenched.
Tax-transfer policy does not operate by means of tax rates alone, but rather operates on the basis of disposable income. It is a household budget comprising of earnings, income tax, social contributions, cash benefits, housing support, family payments and rules for withdrawal. There are situations where a tax cut will benefit the taxpayer despite another tax cut. The appropriate object in poverty and work benefits is therefore the full budget constraint of different income groups of the household.
Public-economics assumptions are further complicated in the case of two-sided markets as the presence of one group of users influences the other. When a tax is imposed on one side, prices, fees, commissions and/or the quality of services on both sides may change. Consequently, there is little guidance in legal incidence to provide in the area of final economic incidence. Household microsimulation must be complemented by an analysis of market structures for tax-transfer reform for platform workers or consumers.
Fiscal sustainability is still included in the equity calculation. Persistent deficits can result in inter-generational transfers of costs, and poorly-targeted tax cuts can result in loss of revenue required for high-demand services. Sustainable reform defines a sustainable financing mechanism and explicitly makes distributional decisions. That way poverty reduction, incentives, and public service funding can be evaluated as a set of related goals and not as competing goals or slogans.
The people affected by interacting rules are at the heart of that analysis and have come to be known as microsimulation. Treasury has implemented the tax and welfare settings in the New Zealand Treasury's TAWA model and has used the model for distributional analysis, fiscal incidence analysis and effective marginal-tax-rate analysis. OECD work also provides a picture of the many different advanced administrations that have used tax-and-spending microsimulation. These tools allow for reform debates to be made more real in terms of impacts at different income deciles, different family types, and different labour-market positions.
Support that is focused creates conflicting pressures for policy to reduce poverty and/or to increase work incentives. A generous benefit provides protection to low incomes, but fast tapers off as income increases – potentially leading to a high effective marginal tax rate. That rate is the percentage of an additional unit of income lost as a result of an increase in taxes and a decrease in transfers. High rates do not indicate that employment declines, but rather when there is a disproportionately small increase in disposable income from an increase in employment.
Generosity is not the sole criterion of design quality, as it is withdrawal shape. Gradual tapers can help to make a transition into a workplace smoother, abrupt thresholds can help to create cliffs that impact on hours, timing or formal reporting. Family-based transfers can better target the needs of the household while individual taxation can better enhance incentives for those who provide secondary earnings, in some contexts. There are therefore trade-offs between equity, fiscal cost of the policy, targeting and administrative simplicity.
Economic welfare is a broader measure than jobs. The costs of commuting, childcare, health, and lost leisure all impact household welfare, as do any additional costs of work in raising output and income. An approach which boosts labour supply by imposing high benefit sanctions might appear to be successful in terms of employment, but at the same time reduce income security for a targeted group. The combination of employment, hours, disposable income, poverty depth and fiscal cost are thus followed by strong evaluation.
There is a political layer added by public choice. Narrow tax concessions can be focused and apparent to the beneficiaries while costs can be diffused across a wide tax base. Modelling of weak social value can make it harder to reform the structure to make them more efficient. Transparent distributional analysis can help by making the amorphous fiscal cost more concrete and understandable, and then putting it up next to other uses of the revenue.
The importance of mobility stems from the fact that families experience income mobility over time. Temporary low income may be due to study or caregiving circumstances, job instability, or because people are starting out in their careers, but persistent low income is a distinct policy problem. Tax transfer modelling for one year may not recognise all life-cycle effects. Longitudinal evidence helps to clarify whether support helps to alleviate temporary poverty, to reduce chronic poverty or to alter the opportunities for people to get out of poverty.
Another connection between the design of welfare and long-run productivity is the human capital aspect. The short-run fiscal costs of transfers that involve nutrition, housing, childcare, or education participation can be balanced with impacts on earnings in the future.Even if short-run fiscal accounts show a cost, transfers involving nutrition, housing, childcare and education participation can support future earnings. On the other hand, benefit rules which discourage or penalize the investment of skills can stifle skill investment. A serious work-incentive programme should not only focus on labour supply in the short run, but also look at how the rules apply to creating earning capacity in the longer run.
Public economics also cautions against seeing all the behavioral reactions as socially valuable. Any change in tax that boosts formal labour supply can affect informal care within the household, alter childcare demand or have an impact on the market power. The two-sided nature of markets adds to the complexity and can mean a tax on a platform or provider impacts more than one side of a transaction. Incidence is not just about the legal taxpayer in the legislation but also on elasticities and market structure.
The distributional tension is apparent in consumption taxes. Relatively high consumption taxes can be an efficient method of raising revenue, but they can also cause poorer people to spend a higher percentage of their current income. Lower rates for "necessities" can lessen that burden, but also benefit high spending households by substantial absolute amounts. When payment rules are clear and administrative systems are able to accurately and consistently identify eligible households, targeted transfers can more directly address regressivity.
A progressive assessment of progressivity should thus be made in the overall fiscal system. The final pattern can be different: personal income tax is progressive, whereas consumption taxes, payroll contributions, housing subsidies or benefit withdrawal are not. New Zealand fiscal-incidence work shows why it is useful to track taxes and benefits by household income and not consider them individually. The same can be done to determine whether an ostensibly progressive reform increases or decreases annual inequality or does not affect it at all.
Admin structure can impact on outcomes as much as statutory generosity. Changing circumstances, unexpected reconciliation, debt collection and delayed reassessments can make it difficult to take up or difficult for them. While automatic data matching and pre-filled data can help ease access to digital systems, there remain language, disability, connectivity and record-keeping barriers that require alternative ways for others to access the data. A welfare reform, if it is to have any intended effect, must ensure that eligible households can be accessed and that they are able to access it and understand it.
Modelling is the most effective reform package as a decision making tool, not a frill at the end of the package when policy decisions are already made. Distributional tables, effective-marginal-rate profiles, behavioural sensitivity tests and fiscal scenarios can be generated prior to legislation. This information can then inform the design of thresholds, taper rates, refundable credits and transition rules. Political decisions can't be removed from evidence, but evidence can reveal hidden trade-offs and limit the possibility of a single headline leading to the creation of a complicated household reality.
The subtler message is that the design of the tax system should be evaluated by observing the behavior, not by the name of the statute. This distinction is important because legal form and economic incidence may be counter-invariant once the household or the firm adjusts. An additional protection is to explicitly state the assumptions so that others can re-create or dispute the main conclusion. The strength of the evidence also is improved when distribution, administration and behaviour are considered together, as opposed to in separate reports.
Evaluation criteria are better understood if agreed in advance with beneficiaries and administrators when administrators adapt around a permanent policy. The test is whether a reform can be defended, when the financial, distributional, complexity and uncertainty costs are all on the same page. Thus, good design will not make transparency a post policy communication exercise but a part of the policy architecture. One other benefit of this is hidden trade-offs emerge before thresholds, exemptions or enforcement settings become routine.
The deeper thought is that design of the fiscal benefit should be evaluated in relation to real behaviour, not as a matter of theory in relation to labels listed on the statute book. That is important because legal form and economic incidence may go in different directions as households or firms react.
CITE THIS ARTICLE
Sultana, K. R. (2026). Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice. https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d
K. R. Sultana, “Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice,” 2026. [Online]. Available: https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d
Sultana, K. R. (2026) ‘Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice’. Available at: https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d
Sultana, Kazi Rukaiya. “Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice.” 2026, https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d.
Kazi Rukaiya Sultana. “Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice.” (2026). https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d.
Sultana KR. Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice. 2026. https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d
@misc{article_8111e471520e511e94068476393b7a2d,
  title = {Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice},
  author = {Kazi Rukaiya Sultana},
  year = {2026},
  url = {https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d},
}
TY  - GEN
AU  - Kazi Rukaiya Sultana
TI  - Tax-Transfer Reform, Poverty Reduction, and Work Incentives: Evidence from Public economics, taxation in two-sided markets, public choice
PY  - 2026-01-14
UR  - https://researchbysultana.com/article/8111e471-520e-511e-9406-8476393b7a2d
ER  -
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life