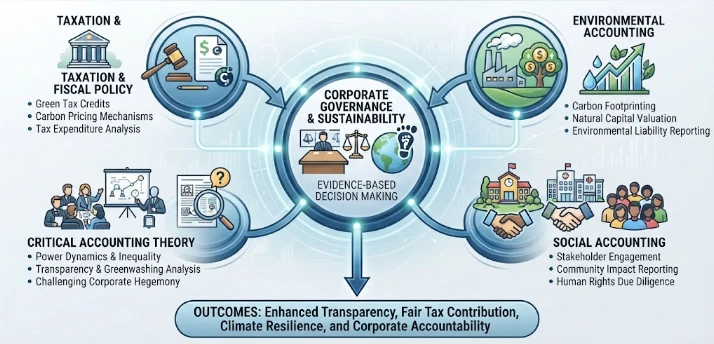
This article connects climate risk with taxation, environmental accounting, social accounting and critical accounting theory. Physical hazards and transition policies can change asset values, operating costs, insurance, supply chains and public budgets, making climate policy a fiscal as well as environmental issue. Tax credits, accelerated depreciation and other incentives can lower the private cost of low-carbon investment, but their public value depends on additional emissions reduction, resilience and credible measurement. The article argues that social and environmental accounting can reveal workforce, community, energy, biodiversity and remediation impacts that ordinary financial ratios may miss. Critical accounting theory adds a warning that disclosure boundaries, baselines and materiality choices influence what stakeholders can see. Corporate claims therefore need to be checked against tax records, investment data, engineering evidence and recognised reporting standards. The article also addresses distributional impacts, climate-adjusted public investment appraisal, climate finance and contingent fiscal risks. Strong accountability requires consistency across tax returns, financial statements, sustainability reports and environmental outcomes, together with transparent fiscal costs and periodic review of incentives.
Climate risk is now a fiscal and corporate-governance concern because physical risks and transition policies have the potential to impact asset values, operating costs, insurance availability, supply chains, and public budgets. The direct costs of floods, heat, storms, droughts and wildfire losses change relative prices across energy, transport, buildings and industry through decarbonisation policy changes. Carbon pricing, investment allowances, excise design, accelerated depreciation and targeted credit are all elements of tax systems that reside within that adjustment. A credible framework thus links climate economics to tax incidence and accountability, instead of environmental incentives as individual "gifts.A credible framework thus ties climate economics to tax incidence and accountability, as opposed to environmental incentives as separate “gifts.”
This is particularly the case if tax credits are offered for low carbon investments. Public case is determined by the emissions reduction or resilience value created, but private costs of equipment are reduced by depreciation schedules, investment credits and exemptions. Social accounting incorporates impacts on workers, communities, and energy affordability, and critical accounting requires identifying impacts that are not within the accounting boundary. A green tax incentive is only as believable as the measure employed to capture and validate the desired green outcomes.
The performance of the firm needs to be evaluated on a timescale that reflects transition costs and resilience benefits. Energy costs, regulatory liability or disruption risk can be lowered by investing in the environment, but short-run accounting returns may be lower when investing early. A one-year profitability test can thus be limiting investments with long-term value. Simultaneously, however, not all environmental projects have an effect on competitiveness, and as such claims need to be substantiated by evidence regarding productivity, operating costs, revenues, financing conditions, and risk reduction, not by general statements on sustainability.
Green incentives are also affected by tax administration. Technical parameters like equipment type, emissions intensity, project timing, or certification may affect eligibility. Revenue agencies want knowledge and information that goes beyond the traditional accounting books, and firms want rules to be clearly documented prior to investment. Pre-approvals, standardised certificates, information sharing with sector regulators and post-claim verification can help to mitigate uncertainty. When the conditions to be met are well defined and align with measurable results, simpler design can lead to improved take-up without compromising integrity.
A good climate-tax policy is thus necessarily accompanied by an exit plan. The costs of technology, market penetration, carbon price change over time and regulation is just as likely to become redundant or distortive, so an incentive that works at introduction can be redundant or distortive later. Schedule evaluation and sunset clauses provide opportunities to change rates or eligibility before rate becomes politically entrenched in fiscal. The incentive should be compared with other options like direct grants, standards, public procurement, carbon pricing or infrastructure investment. It's not a matter of preference but the best tool for a given barrier that is being used.
Environmental tax incentives can help to speed up investment if they remedy a market failure and if the eligible activity is sufficiently well-specified so that the windfall effect is minimized. Bad incentives can pay for projects that are already commercially viable; can incentivize relabelling; or can give an advantage to firms with more tax capacity than firms providing the greatest environmental benefit. Real access is determined by refundability, carry-forward provisions, investment thresholds and interaction with grants. Evaluation must be additional, emission outcomes, distributional effects, fiscal cost and administrative complexity must all be on the same scorecard.
The quality of sustainability information is becoming more and more a factor in determining corporate accountability. Effective from 2024, IFRS S1 and IFRS S2, which were issued in 2023, provide a structure for disclosure around Governance, Strategy, Risk Management, Metrics and Targets. The IFRS S2 distinguishes physical climate and transition risks, and links them to cash flows, access to finance and cost of capital. The architecture also has relevance to tax policy because the easier it is to analyse whether a claimed green investment incentive works, the more likely it is to be analysed.The architecture also has relevance to tax policy because the easier it is to analyse whether a claimed green investment incentive works, the more likely it is to be analysed.
Rebound and substitution are also important elements of corporate accountability. Efficient operation will reduce operating expenses and boost activity, and a subsidised clean asset can displace another investment that would have taken place with no subsidy. Evaluating should be based on a counterfactual and not on the number of projects funded. Regulators will have a better footing to determine where and when to allocate more resources to transition activities and how to separate them from what they've been whistled as ‘business as usual’ spending once they combine the tax data with sustainability metrics, investment timing and operational performance.
Social and environmental accounting includes the analysis of more than profits. An economic impact from energy use, emissions, workforce impacts, community exposure, pressure on biodiversity and remediation obligations can only be indirectly seen in the ordinary financial ratios. Environmental accounting is not an alternative to financial accounting but it provides further information to help assess whether reported performance is affected by external costs that are not priced. Tax incentives that are tied to such information can help to optimize the allocation of capital and a weak tax base can be transformed into a branding subsidy through fiscal support.
Critical accounting theory provides a helpful reminder of the issues of power and framing. Choices made about what is considered material, what is within the scope of disclosure, what constitutes a baseline and what constitutes a metric affect what is visible through disclosure systems. A business can claim to be reducing operational emissions whilst they are increasing in the supply chain; or they can trumpet a small green portfolio whilst a bigger high-carbon business is doing nothing. Fiscal authorities, in turn, require definitions that are not bound to promotional stories and are verifiable with the tax data, engineering evidence or recognised reporting standards.
Climate and disaster economics also transforms the issue of public finance from the average annual spending towards tail risk. Emergency expenditures can be sizable while tax revenues are being squeezed during severe events. Disaster risk financing involves establishing liquidity after shocks through the use of instruments like reserves, contingent credit, insurance, catastrophe cover, and budget reallocations. The goal is not just quicker relief, but to prevent the disruptive adjustment the fiscal way when regular revenue suddenly weakens.
The importance of distribution: Climate policy and Climate shocks are not necessarily neutral across income groups or regions. Lower income households may have a higher proportion of their current income dedicated to energy taxes, while higher income households may have more resources to invest in more efficient vehicles, insulation, rooftop generation, or other eligible investments. Those imbalances can be mitigated through targeted transfers, refundable tax credits, and public investment. An instrument should not be considered as fair solely for its environmental label, but should be analysed in terms of household budgets after taxes, prices, and compensation.
The discipline must be applied to public investment decisions as well. The cost of resilient infrastructure may be higher during construction, but can lower expected losses, service disruptions, and reconstruction costs over the life of an asset. That value is underestimated by conventional appraisal if it fails to account for the possibility of disaster, network effects or the distributional consequences. The finance ministries have more of a basis to compare prevention with repeated repair when using climate adjusted cost benefit analysis. Assumptions which can be transparent are crucial, as the projections of hazards and discount rates can have a material impact on the results.
The additional layer of accountability comes from climate finance as threats of public guarantees, concessional loans, blended finance and tax incentives move the risks from taxpayers to private investors. Strong contrast can create projects of high social value, weak contracts can socialise downside risk and leave most upside private. The fiscal control is reinforced by the clear additionality tests, performance milestones and clawback provisions, as well as disclosure of contingent liabilities. The risk sharing is more effective as a public support if it is not embedded in a complicated financing mechanism.
A robust accountability test is that there is consistency across tax returns, financial statements, sustainability reporting, investment decisions and environmental outcomes. If a firm is claiming to be a climate leader, but the incentives are unclear or the metrics are low, there is credibility risk, and if a government is encouraging green investment, but it doesn't disclose fiscal costs, then there is the same risk. Good policy involves tying environmental goals to real data, distributional analysis and public-budget discipline. This combination makes climate taxation a tangible element of economic transition planning.
The fiscal cost, fairness, behaviour and administrative burden are best considered together in the same evaluative setting, that is, in the same policy story.
CITE THIS ARTICLE
Sultana, K. R. (2026). Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory.. https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027
K. R. Sultana, “Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory.,” 2026. [Online]. Available: https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027
Sultana, K. R. (2026) ‘Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory.’. Available at: https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027
Sultana, Kazi Rukaiya. “Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory..” 2026, https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027.
Kazi Rukaiya Sultana. “Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory..” (2026). https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027.
Sultana KR. Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory.. 2026. https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027
@misc{article_d0f70eeec6e755ce87e41c97b9d64027,
  title = {Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory.},
  author = {Kazi Rukaiya Sultana},
  year = {2026},
  url = {https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027},
}
TY  - GEN
AU  - Kazi Rukaiya Sultana
TI  - Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Taxation, social, environmental accounting, critical accounting theory.
PY  - 2026-10-26
UR  - https://researchbysultana.com/article/d0f70eee-c6e7-55ce-87e4-1c97b9d64027
ER  -
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life