Fair tax is usually measured in rates, brackets, exemptions and revenue totals, but when it comes to vulnerable taxpayers, fairness is being attained in a far more visceral way: that rules are comprehensible, obligations can be met and errors rectified without undue consequences. Tax law is the formal architecture, tax policy is the formal architecture, but tax clinics show how the formal architecture works when put to the test. Debt, late filing, unstable income, small-business failure, family disruption, disability, and lack of counsel all reveal a core principle of fiscal justice in these cases. Equal rules are not equal in what they put into practice.
Fiscal justice relates to both revenue collection and burden sharing, and the provision of procedural safeguards. Effective taxation is crucial for social protection and public services, which is why it is important for collective wellbeing. Enforcement, meanwhile, is "coercive power.
When a taxpayer doesn't have the resources or is not educated about these penalties, interest, garnishment, recovery action and formal disputes can have a serious impact. A viable system must thus have both revenue integrity and proportionality. Deliberate non-compliance should be accompanied by mechanisms for correction, hardship management, review and education in the event of non-compliance due to confusion, vulnerability or temporary crisis that does not require the strong enforcement otherwise required.
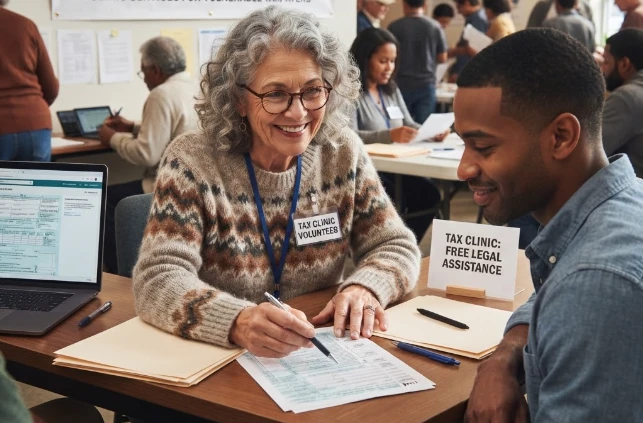
Tax clinics offer a window of practical experience of that balance. The National Tax Clinic program provides free tax advice to eligible people and small businesses who are unable to seek tax advice through other means. Clinics are based on the university and supervised by professionals, while students are helping with actual tax issues.
Services may encompass returns, historical lodgements, tax debt, payment options, company registrations, conflicts and liaison with the Australian Taxation Office. This type of work shows that tax access is not restricted to the form completion process. Financial history reconstruction, notice interpretation, negotiation and recovery of future compliance are common requirements.
Vulnerabilities in taxation are seldom unique qualities. Low income may be coupled with poor digital access, limited English proficiency, unstable housing, mental stress, insecure work, caring duties, recent migration, business failure, or by limited financial literacy. A small business owner may be in possession of valuable equipment, but unable to have cash available to handle an unexpected liability.
There are various types of streams of income that a worker may earn and that will be treated differently upon receipt. Access to records may be lost if someone moves out of a challenging family situation. For routine cases, standardisation is efficient; fiscal justice calls for a certain level of discretion and assistance to address the times when stable assumptions come undone.
The implications for policy design are that point. Governments tend to rate a tax move on the basis of the estimated amount of money to be raised, the efficiency in which the tax is levied, the cost of compliance, and the incidence on income groups. Those tests are essential, but accessibility should be a co-equal consideration with those tests.
An inconsequential revenue increase can cause substantial hardship if the eligibility rules are obscure or correction procedures are cumbersome. Similarly, if it is intended to be a concession for low income groups, it can turn out to be a failure if the conditions of acceptance are too complicated. Take-up, the risk of errors, the documentation burden, pathways to disputes, and independent assistance are therefore factors that must be taken into account in the design of effective tax policies before they are implemented.
Digitalisation enhances opportunity and risk. Online accounts, pre-filled data, electronic filing, auto reminders and integrated payment systems can save the regular compliance expense. OECD efforts on digital tax administration have focussed on possibilities for technology to make tax easier and more seamless.
However, digital-first systems can be a disadvantage to taxpayers who do not have devices, don't have access to devices, don't know how to use them, don't have confidence in them, don't speak the language, or are unable to navigate through identity verification. When reasoning is not clear, it may be more challenging to challenge automated decisions. There must be alternatives that are easy to access, explanations that are easy to interpret, mechanisms for correcting the problem, and human oversight for complex situations in a fiscal system.
Tax clinics can function as a conduit that bridges that divide. A clinic can provide support to a taxpayer in the following ways: to understand a digital notice, to collect evidence, to make corrections to a notice on the web, or to communicate with the revenue authority. Most important, repeated clinic cases highlight design issues. If a large number of clients interpret and/or take the same action as a result of a misunderstanding or miss the same deadline or run into the same hurdle in the portal, the problem may be more indicative of a systematic barrier than a lack of care or sophistication on the part of the clients. Client confidentiality is thus maintained and aggregated clinic evidence can then provide direction in service design, helping to guide administrative guidance and future law reform.
A special focus is debt administration since debt can easily become a social problem if it is not handled properly. But interest and penalties add up to increase the debt, and financial strain can diminish response. A rigidly designed collection process, while it may help to increase recovery in the short term, can actually exacerbate business failure, housing instability and household burden.
A clinic can verify if the debt is accurate and may establish whether or not there are any reviews that can be obtained, which would include a realistic method of payment, and explain the ongoing obligations. Such intervention does not wipe out civil and criminal responsibilities. Rather, it is a tool that can lead to a resolution which is more likely to obtain payment and maintain basic economic stability.
The same reasoning applies to penalties. Penalties serve an important function in a system: They help to reinforce or discourage adherence to the rules and can be used to build confidence among taxpayers who are complying. But proportionality is important as identical penalties can have wildly varying effects depending on income and situation.
The remission, reasonable care, hardship and/or review rules must be clearly defined and applied uniformly. Independent support will enable the taxpayer to present evidence and will assist the administrators to get a better picture of the facts. Fair procedure reinforce compliance legitimacy in the sense that taxpayers are able to observe a way to rectify a genuine error without having to anticipate forgiveness or immunity.
Clinical education also helps develop professional ethics. The battle between technical and human consequences is a situation that a student will face when they are working with vulnerable clients. Professional responsibilities include client autonomy, confidentiality, accurately giving advice, managing conflicts, carefully documenting, and being independent.
Exposure to complex real cases can help to develop judgement skills which are not fully able to be simulated in the classroom. Future tax professionals, including those who will be accountants and lawyers, also have a deeper comprehension of the way poverty, debt, disability, migration, or business stress play out with tax administration. That experience can shape a lawyer's subsequent practice and expand the tax profession's role in access to justice.
An advanced fiscal-justice system should do more than simply calculate collection yields. Some of the useful indicators are: voluntary compliance, time needed to clear conflicts, take up of assistance, sustainability of debt, error correction, availability of service, understanding of taxpayer, and distribution of administrative burden. Any data should also provide details on the delay or difficulty vulnerable groups face in exercising review rights. This evidence can be used to support targeted reform without compromising the general obligations. Risk based approaches for compliance are being leveraged by revenue agencies and can be applied to the identification of access barriers.
It is crucial to have cooperation among institutions. The revenue authorities have their own knowledge, the universities have theirs, professional bodies have theirs, community legal centres, financial counsellors, migrant services, disability organisations, and small-business networks all have their own types of knowledge. Expanding the referral process can help to quickly link a taxpayer to the appropriate service in a timely manner, before escalation occurs.
Frontline organisations can gain from training to see tax issues early, before they can get to a point where serious debt is created. Stable funding can enable clinics to have a supervisor on staff, build a safe system, ensure continuity between reporting periods, and process cases that do not have a short academic calendar or one-semester resolution. Careful deliberate planning in regional and remote areas is needed, through hybrid delivery and trusted and durable local partnerships.
By July 2026, tax clinics illustrate a more general tax access principle. Revenue systems are legitimate if the responsibilities are transparent, the enforcement is reliable, and the opportunities for advice and remedy are truly accessible. Vulnerable taxpayers need no second-rate tax system with a lower standard of conduct; fair treatment can be achieved without a system that allows taxpayers to avoid paying taxes, but confuse their tax responsibilities, or allows taxpayers to avoid paying taxes in the event of a crisis, as opposed to being unwilling to do so, or willing to do so, but unable. Fiscal justice is made possible when the law, administration, professional support, policy evaluation collaborate in a way that compliance is not only a reality but a reality that is not too difficult to reach.