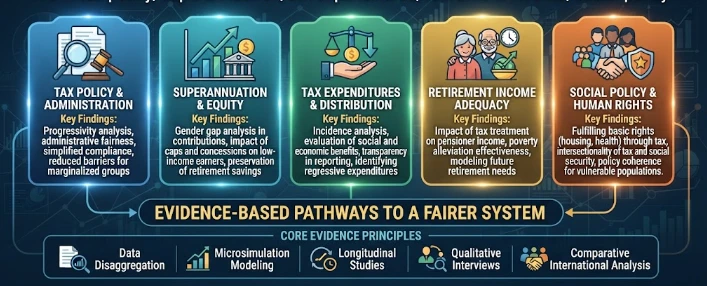
Rates and redistribution is frequently the lens used to discuss tax justice, but procedure is the starting point for access to rights. A tax payer must be aware of an obligation, be able to obtain records, communicate with an authority, challenge an assessment and obtain review at no undue burden. Formal equality can become actual inequality if the advice of professionals is required for participation to be at the level of basic. Access-to-rights analysis thus examines the possibility of the protections found in tax law being used by people of average means and by “small entities.”
Superannuation concessions are supposed to incentivise retirement saving, but there is variation in super capacity across the income distribution. Those who earn a low wage or had a spell of unemployment cannot reap the same benefit from contribution-based concessions as a high income earner with a large amount of disposable income. Tax-expenditure reporting highlights that fiscal support. The question of whether concession design fits into a framework of public pensions, housing security and low-income retirement support is then posed in social policy analysis.
Small companies are especially burdened with a unique access issue as legal requirements can feel like those of larger companies, but being without the expertise. The registration for GST and payroll, deductions, record keeping, and entity selection can add up. Tax clinics and easy guidance can save you from falling into the debt trap with small issues. The long-run solution is still simpler, since the support services must not be a permanent cost of unnecessary complexity.
Another aspect of access and distribution is evident in retirement policy. Superannuation or retirement saving concessions can help to provide long term retirement income security, but the fiscal value depends on many factors including contribution capacity, tax rates, and account balances. Deductions that depend on current contributions are only of limited value to lower-income workers. In fact, fair design also takes into account refundable offsets, contribution caps, preservation rules, age, housing costs and the interaction with public pensions.
There is also an advanced tax law question regarding certainty—namely, should certainty not exist for someone who is not able to hire a specialist interpreter? Private rulings, public guidance, safe harbours, and published administrative positions can help limit uncertainty, as long as they are widely available and not inconsistent. With too much discretion, there's risk because there's possibility of different facts giving different results. Transparent interpretation is thus a mechanism of justice and an efficiency measure in the administration.
The enforcement should be proportionate. There is a balance to be struck between taking vigorous action against those who deliberately evade and the consequences of coercive measures when imposed on those who are under real hardship or misapprehension. There must be protections, oversight and definite escalation guidelines for debt collection, penalties, garnishment and litigation. A rights-based system does not conflate every issue with the moral one of inability, mistake, avoidance and fraud.
Reform receives credibility when access indicators are side by side with revenue indicators. Administrations can monitor the resolution of complaints, outcomes, processing time, debt, digital exclusion, clinic referrals and reoccurring error types. This information can give insights into how legal changes either smooth out friction or move it elsewhere. Tax justice is not then just about the abstract argument of tax rates, but about the day-to-day working of institutions.
Fairness with regard to retirement income also needs a lifetime perspective. Investment earnings and income from current tax concessions can add up over time and cause significant disparities after a long time. Final outcomes are influenced by contribution caps, earnings-tax rules, refundable low-income support and pension means testing. It should be noted that, rather than being assessed on an annual income basis, reform should be evaluated across age and income groups.
Tax clinics fill that void. The National Tax Clinic is government-funded to provide access to services for eligible people and small businesses requiring assistance in relation to tax matters. Clinics also provide learning experiences for supervised students and produce documentation of the recurring administrative issues. This is important because casework can identify, individually, issues with debt, record keeping, registration, family situations, digital access, or miscommunication of legal notices.
There is a second layer of justice, that of tax literacy. Being aware of the filing dates, deductible expenses, business registration, instalments, and review rights can avoid needless debt and penalties. The use of literacy to replace simple law is not suitable; even an informed tax-payer would find it hard to understand rules with many definitions and exceptions. Good systems provide clear instructions and appropriate responsibilities and easy access to professional or community assistance.
Voluntary compliance is also influenced by procedural fairness. Where reasons are clear, evidence is taken into account, there are review channels that are credible and communication is respectful, people are more likely to accept an adverse outcome. The field of behavioural tax research has therefore progressed from a limited fear of tax audit approach. Enforcement cannot replace trust, but uniform process can improve the sense of fairness and provide a better perception of fairness in enforcement.
Gender budgeting extends the tax-justice lens by considering what the formal, neutral rule means for labour-market and household dynamics. Incidence can be affected by differences in employment, family caregiving, retirement saving, home ownership, and consumption. However, a budget which is distributionally unequal may not include an explicit gender distinction. Questions of who gets concessions, who pays consumption taxes, who is eligible for tax credits, and how policy affects the ability to engage in care-taking and lifetime earnings are part of gender-aware analysis.
Public finance brings the spending side to the fairness equation. The concept of tax justice cannot be limited to who pays for taxes as taxes are the financing mechanism for health, education, infrastructure, income support, security and administration. Fiscal-incidence analysis can be used to connect taxes and benefits and deduce the overall impact on the household resources. It also discourages the kind of simplistic notions that a particular tax is fair or unfair without looking at the services and transfers provided by the system as a whole.
Disclosure and governance are areas of intersection between company law and securities regulation and tax justice. Overseeing these auditors, regulators, tax authorities and investors, the corporate reporting shapes what they can see. There are many aspects of risk assessment that can be significant, including related party transactions, executive incentives, provisions, deferred tax, and uncertain tax positions. There is no need to say that aggressive tax planning is not a product of weak governance, but transparent responsibilities and credible oversight makes hidden strategies difficult to maintain.
The practical test is equal ability to engage in the tax system. That standard demands that rules be understandable, assistance be within reach, decisions be transparent, review be effective and, prior to reforms, distributional analysis be performed. It is still very much important to collect revenue, as public services need revenue, but collecting revenue is legitimate if rights are viable. A tax system wins confidence when it is not so complicated, it not so powerful, and fiscal decisions are not so closed off to examination between income and organizational lines.
The other benefit of this approach is that hidden trade-offs become apparent before thresholds, exemptions or enforcement settings become routine. The deeper message is that fiscal design should be challenged by empirical evidence of behaviour and not presumed based on the label. This distinction is not insignificant, since, when households or firms adjust, legal form and economic incidence can go in opposite directions. Another protection is to be explicit about the assumptions that underlie the main conclusion, so that other parties can be able to repeat or question the analysis.
It becomes easier to build the evidence when distribution, administration and behaviour are viewed in combination as opposed to reporting on these separately. Agreement on evaluation criteria prior to adaption by beneficiaries and administrators in the face of a permanent rule contributes to policy durability. So the question is really whether a reform is defensible on the fiscal cost, distribution, complexity, and uncertainty side of the equation. So good design makes transparency a component of policy structure, not an act of communication once the policy is in place.
The other benefit of this method is that the hidden trade-offs are exposed before thresholds, exemptions, or enforcement rules become "business as usual. The more profound message is that fiscal design should be evaluated with the real behaviour, not assumed on the basis of the statutory labels. The legal form and economic incidence may go in different directions once households or firms have responded to change because of this distinction. Another protection is to make assumptions explicit and accessible to other analysts to replicate and critique the main conclusion.