From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research
Kazi Rukaiya Sultana (Master of Public Policy & Master of Social Welfare and Research)
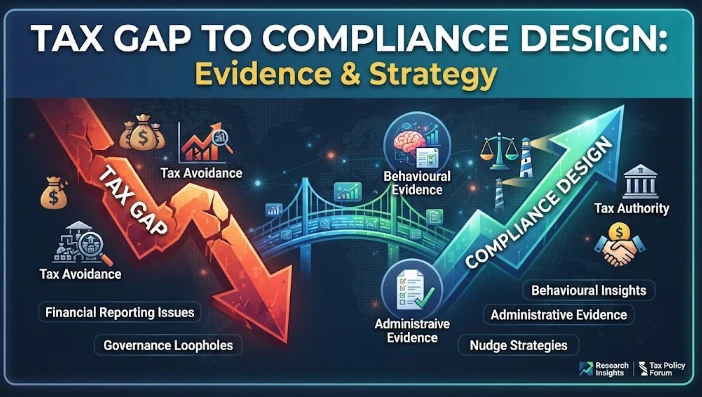
This article connects tax-gap analysis with financial reporting, corporate governance and research on tax avoidance. It cautions that book-tax differences are not automatically evidence of aggressive behaviour because accounting profit and taxable income can diverge legitimately through depreciation, losses, tax credits, exempt income, consolidation, foreign operations and timing rules. Financial statements can therefore provide risk signals, but tax administrations need additional evidence before drawing conclusions about motive. Using Australian GST-gap estimates, the article again distinguishes errors, payment problems and deliberate concealment. Behavioural factors such as trust, clarity, fairness and cash-flow pressure interact with penalties and audit probability, while compliance costs can push smaller firms toward mistakes or informality. Risk segmentation is recommended so simple errors receive correction, temporary payment stress receives workable arrangements and intentional concealment receives stronger verification. Corporate governance matters because boards and audit committees approve transactions and set risk appetite, but external audit and tax enforcement have distinct roles. Tax expenditures and special rules can create further classification boundaries. Effective compliance design combines accounting evidence, behavioural insight, targeted administration and proportionate enforcement.
A tax gap is not just a number of figures. It is a difference between the amount of tax that is supposed to be levied according to the current laws and the amount of tax collected (in accordance with the estimation method that an administration has) OECD Tax Administration 2024 says that many places are increasing the number of estimates to gain insight into the extent and type of noncompliance. The policy value is derived from the diagnosis: There are gaps to be filled, data sources to be used, service strategies to be adopted, and enforcement responses to be made, and these vary according to the gap.
Financial reporting and taxation are subject to different rules and therefore, book-tax differences need not be a sign of avoidance. There are legal differences between accounting profit and taxable income that can arise due to depreciation schedules, loss recognition, tax credits, exempt income, consolidation, foreign operations, or timing rules. When strategies for shifting income, inflating deductions, or taking advantage of mismatches are removed from the picture, the research becomes more reliable when the differences in the structures are separated. While financial statements give signals, additional data are needed for tax administration to draw conclusions about motive.
The published work on the tax-gap in Australia demonstrates why estimation can't be outside of rather than in compliance design. The November 2024 ATO release estimated the net GST gap at approximately 7.9 billion Australian dollars (around 9 percent of theoretical GST) for the 2022–23 financial year. The agency also noted that historically small businesses made up a significant proportion of the gap in the GST returns, highlighting the need for both quality and cash transactions, as well as GST registration behaviour, to be monitored as risks. Even with a gap estimate, it remains unclear why an error, a problem with a payment or deliberate concealment took place and administration should not consider all of these as the same behaviour until they have additional evidence.
The traditional deterrence model is complicated by behavioural evidence. Penalties and audit probability are important, but so is compliance when it comes to clarity, trust, perceived fairness, social norms, cash-flow pressure and ease of completing obligations. OECD work on tax-administration indicates that the use of behavioural researchers and targeted communications is growing. If you can anticipate the error at the right time, you can save the cost of that error, and complex rules can cause errors, that in the aggregate look like evasion in data.
The costs of compliance should also be considered, as administrative hassles may make small businesses more prone to making mistakes or becoming informal. Even if there is no extra tax to pay, time spent interpreting rules, keeping records, reconciling GST and correcting returns have an economic cost. While digital filing can alleviate a lot of the burden of routine, it can only do so if software, identities and data standards are reliable. Ineffective digital obligations may just transfer costs from the government to businesses and professional advisers.
Risk segmentation provides a more proportionate model. Those whose errors are simple must be educated and corrected, those whose payment is only temporary must be provided with working out, and those which have been deliberately concealed must be met with a greater degree of verification. There is no need for the agency to dedicate resources to investigating each discrepancy when it is fraud; that can lead to lost voluntary compliance. Addressing each and every discrepancy on the innocent level is the opposite of the problem as it undermines deterrence and fairness for taxpayers who aren't being targeted for intervention.
That evidence is impacted by corporate governance as the board determines the level of risk appetite and approves transactions that may involve significant tax consequences. Audit committees should have access to information on unasserted tax positions, aggressive tax arrangements, significant tax disputes, transfer pricing, and the effectiveness of tax controls. The financial-reporting effects are analysed by external auditors and revenue authorities utilise tax law with different information. Strong governance also appreciates those separate roles, and does not assume because of an unmodified audit opinion that all tax positions are low risk.
Special rules increase boundaries and so do tax expenditures. Classification questions and opportunities for planning arise through deductions, exemptions, reduced rates and sector concessions. Each additional boundary provides a legitimate area of uncertainty and an opportunity for aggressive interpretation. Thus, fiscal authorities should consider partly the administrative dimension when assessing tax expenditures: a relatively low policy value concession, but of high complexity, can trigger costs much higher than the revenue amount included in the budget statement.
Transaction trails are advantageous in the context of GST and VAT systems. While invoice chains can offer third-party information for verification, there are still issues such as cash in transactions, missing traders, refund fraud, and classification disputes. E-invoicing and data matching can enhance the visibility in the areas where legal and technical requirements are well established. However, some robust safeguards remain important, as big data can amplify mistakes, raise privacy issues, and produce false positives when the models used to calculate risk are not given any context.
A second level is added with fiscal federalism, in which several governments share their tax bases or administrative functions. Variations in definitions, rates, exemptions, and data systems can create compliance complexity for those businesses conducting activities in multiple jurisdictions. Coordination can minimize duplication of efforts, for example by shared application of the register, the exchange of information, harmonisation of definitions, or a central collecting system. Institutional design is influenced by constitutional tasks, revenue autonomy and the importance of local policy flexibility.
But corporate tax avoidance demands a different toolbox to small-business record errors. Financing structures, intangible assets, entity chains, cross-border mismatches and other structures require specialist knowledge and an understanding of international information to use them for large groups. Raw disclosure and transparency of taxes can help to promote accountability but can be misleading if there is no context as book profit is not the same as taxable profit. Effective assurance encompasses analysis of accounts, interpretation of laws, economic substance, and a risk-based engagement.
The reporting and exchange of information on a country-by-country basis and to a greater extent have improved the data available for high level risk assessment. Any ratio of profit, employees, assets, revenue and taxes can highlight some unusual patterns across jurisdictions, but are not definitive. Knowing the business model and engaging with taxpayers makes data matching more effective. Analytical screening and proportionate verification, reasoned compliance design and dispute rights, rather than automated compliance avoidance, are beneficial.
The credibility of administration can also be affected by governance and corruption risks. Despite the apparent soundness of statutory rules, willingness to comply can be undermined due to selective enforcement, opaque settlements, weak procurement controls, or conflicts of interest. Legitimacy is achieved through the granting of independence, review rights, written processes and the publication of aggregate performance information. The compliance design thus needs to be embedded in a larger rule of law design and not in a narrow collection design.
Measurement should distinguish gross and net gaps, model uncertainty and the impact of administration. The net gap following compliance activity can decrease even if underlying risks are high, and an economic shock can alter both the liabilities and paying capacity. In time series interpretation, consistency of methods and/or clear revisions are required. The transparency of uncertainty and methodology enhances the utility of gap estimates, rather than detracts from it, as stakeholders see what the numbers can and cannot prove.
A contemporary compliance approach, therefore, integrates prevention, facilitation, verification and enforcement. Omissions are avoided with pre-filled data, errors can be reduced by having clear guidance, high-risk cases can be identified through targeted analytics and deliberate evasion can be dealt with through robust sanctions. Revenue, burden, fairness and trust should be used as the standard for each intervention. The aim is not to enforce as much as possible, but to get compliance at the lowest socially and administration cost possible.
The importance of regular evaluation is because the forces of technology, structure, household conditions, and administrative capacity evolve quicker than many statutes. It is important that public authorities communicate uncertainty instead of estimates as forecasts of behaviour or revenue, to enhance credibility. Institutions with the ability to adjust thresholds, processes, and reporting needs in the face of changing evidence are essential for long-term reform, though. A durable system involves trade-offs between revenue protection and accessibility, a predictable procedure and clear accountability for public and private actors.
A proper assessment then maintains a unified analytical lens over legal design, behavioural response, administrative capacity, and distribution. The test is whether the rule generates measurable public benefits once fiscal costs and compliance burdens and unintended consequences are taken into account. Transparency works best when there are assumptions, definitions, limitations and review criteria that are laid out in advance before the policy becomes difficult to change.
CITE THIS ARTICLE
Sultana, K. R. (2025). From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research. https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15
K. R. Sultana, “From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research,” 2025. [Online]. Available: https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15
Sultana, K. R. (2025) ‘From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research’. Available at: https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15
Sultana, Kazi Rukaiya. “From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research.” 2025, https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15.
Kazi Rukaiya Sultana. “From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research.” (2025). https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15.
Sultana KR. From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research. 2025. https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15
@misc{article_54f0ca458bc35fe1b300170d8473ad15,
  title = {From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research},
  author = {Kazi Rukaiya Sultana},
  year = {2025},
  url = {https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15},
}
TY  - GEN
AU  - Kazi Rukaiya Sultana
TI  - From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Financial reporting, taxation, corporate governance, tax avoidance research
PY  - 2025-03-09
UR  - https://researchbysultana.com/article/54f0ca45-8bc3-5fe1-b300-170d8473ad15
ER  -
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life