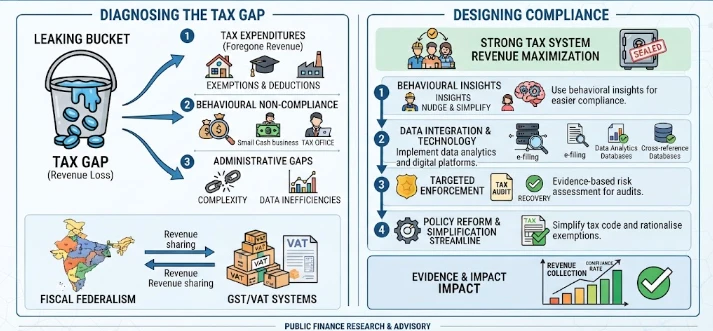
This article treats the tax gap as a diagnostic tool for designing better compliance systems rather than simply a measure of lost revenue. It explains that different gaps require different responses and that fiscal federalism can complicate compliance when several governments share tax bases, definitions, data systems or administrative responsibilities. GST and VAT illustrate how transaction trails, e-invoicing and data matching can strengthen verification, while still creating risks involving refund fraud, cash activity, classification disputes, privacy and false positives. The article distinguishes a compliance gap, where legally due tax is not collected, from a policy gap created intentionally through tax expenditures. It also discusses corporate tax avoidance, transfer pricing, governance and corruption risks, emphasizing that specialist enforcement should be targeted to material risks. Behavioural evidence shows that trust, clarity, cash-flow pressure and administrative burden influence compliance alongside penalties and audit probability. Risk segmentation, transparent methodology and proportional treatment are therefore central. A modern strategy combines prevention, facilitation, verification and credible enforcement while measuring revenue, fairness, burden and institutional trust.
A tax gap isn't merely a revenue number. It is the amount of tax which should be collected according to the existing law but is not being collected based on the estimation method adopted by administration. OECD Tax Administration 2024 states that in many jurisdictions, the rate of non-compliance has been growing and these gaps are now being estimated to help determine the extent and characteristics of non-compliance. There must be different treatments, data sources, service strategies and enforcement responses for the different gaps, hence the policy value is found in diagnosis.
Gap analysis is particularly sensitive to institutional boundaries when it involves fiscal federalism. It's possible to have a central administration of GST or VAT, and the related taxes with regional governments, which can lead to mismatches in definitions and data silos. Those gaps can be minimized by having shared identifiers, interoperable reporting and clear audit responsibility. Cross government visibility is also required for tax-expenditure inventories as one jurisdiction may make a concession, while another jurisdiction is responsible for part of the cost of providing the service to the activity being supported.
Risk segmentation provides a more proportionate model. There is a need to educate and correct taxpayers with simple errors, to work out reasonable arrangements when taxpayers are experiencing temporary payment difficulties and to increase verification of deliberate concealment. Treating all discrepancies as fraud takes up enforcement resources, and can harm compliance. Addressing each discrepancy as a trivial matter exacerbates the issue by reducing taxpayer deterrence and fairness for those who comply, without action.
Special rules multiply boundaries and also have an impact on tax compliance. Classification questions and planning opportunities are provided by deductions, exemptions, reduced rates and sector concessions. Each extra boundary can generate true ambiguity and aggressive interpretation. Partly, however, tax expenditures must be considered from an administrative perspective: A tax concession with relatively limited policy value, but high complexity can have administrative costs much higher than the revenue estimate revealed in a budget statement.
The advantages of transaction trails are seen in the GST and VAT systems. While invoice chains can offer third-party data to assist in verification, risks of missing traders, cash transactions, classification disputes and refund fraud can be significant. In the presence of legally and technically developed infrastructure, E-invoicing and data matching can enhance visibility. They still need robust protection as big data can amplify inaccuracies, lead to privacy issues, and lead to false positives if any context is missing from risk models.
In addition, fiscal federalism adds another dimension in which several governments have overlapping tax bases or share administrative duties. Variations in definitions, rates, exemptions, and data systems can lead to more compliance costs for businesses that do business in multiple jurisdictions. Coordination can minimise duplication in the following ways: Sharing in the registration process; Sharing information; Harmonising definitions of records; Central collection arrangements. The suitable institutional setup will be determined by constitutional duties, revenue autonomy, and the importance of the local policy flexibility.
Tax avoidance by corporations calls for another toolbox, one that's not the same as the one needed for small business record errors. Financing arrangements, intangible assets, transfer pricing, entity chains, and cross-border mismatches, which require specialist knowledge and information from other countries, can all be used by large groups. Disclosures and tax transparency are good for accountability but raw disclosures, without context, can mislead due to the difference in book profit and taxable profit. Effective assurance is the amalgamation of accounting analysis, legal interpretation, economic substance and risk-based engagement.
There should be a difference between compliance gap and policy gap in the public-finance analysis. Tax expenditures are revenue that isn't collected due to a tax exemption; and compliance-gap revenue is revenue that should be collected but does not. The lack of distinction in these concepts results in bad diagnosis. One is for review of the rule itself; the other is about preventing, or serving, verifying, collecting, or enforcing services.
The credibility of administration is also affected by governance and corruption risks. Even though the statutory rules appear to be good, weak enforcement or settlement processes that lack transparency, or conflicts of interest regarding procurement processes, can diminish compliance. Legitimacy is protected with independence, review rights, documented procedures and publication of aggregated performance information. Compliance design must be part of a larger rule-of-law design and not be part of a narrow collection design.
Measurement should involve differentiating gross gaps, modelling uncertainty and the impact of administration. A net gap after the compliance activity may be negative even if there are risks that are high and economic shocks that alter the liabilities and payments capacity. It is important that the interpretation of time series is done in a stable way or there are transparent revisions made. Stakeholders can also appreciate the value of publishing uncertainty and methodology to bolster the value of the gap estimates, not diminish it.
Australia's tax-gap program is a good example of that with very specific estimates of the gap published in the public domain. When it was released in November 2025, the overall level of net gap was approximately 58.2 billion Australian dollars, or 9.1 percent, and was mainly made up of a component for small business of 27.2 billion Australian dollars. There were also significant numbers of people not involved in business and GST. The figures do not mean that all groups are equally non-compliant; they reflect the need for multiple enforcement measures to address the various aspects of non-compliance.
The traditional deterrence model is complicated by behavioural evidence. Against penalties and the probability of being audited, clarity, trust, perceived fairness, social norms, cash flow pressures, and ease of completing obligations are all factors that influence compliance. Tax Administration in the OECD reports that a growing number of tax administration agencies are using behaviourist researchers to make use of targeted communications. When an error occurs at just the right time, it can be prevented at minimal expense; when complex rules result in an error, in aggregate data, that error can be more akin to evasion.
In addition, compliance costs should be given the same attention since administrative hassles might lead small businesses to make mistakes or become informal. Even if no additional tax is due, there is an economic cost that can be incurred for the time spent in trying to interpret the rules, keeping records, reconciling GST, and correcting returns. Routine burden can be reduced through digital filing, but relying on a software system, ID system and data standards that function reliably. Unwieldy digital duties can just be shifted from government departments to business and professional services.
A modern approach to compliance, then, merges prevention, facilitation, verification and enforcement. The absence of omissions is possible because of pre-filled data, the absence of errors because of guidance, high-risk cases identified by targeted analytics, and deliberate evasion can be addressed by sanctions. All interventions should be evaluated by the revenue, burden, fairness and trust. The aim is not to implement the most enforcement; it's to have compliance at the least reasonable social and administrative cost.
Another benefit of this type of practice is that hidden trade-offs can be seen before thresholds, exemptions, or enforcement processes become entrenched in the practice. What is deeper is that the design of the fiscal rules needs to be tested against the actual behaviour, not be assumed through the label of the statute. The legal form of the tax can differ from the economic incidence of the tax because households or firms react differently when the tax is changed. An additional protection is to make the assumptions explicit so that other analysts can either reproduce or debunk the main result.
Distribution, administration and behaviour may also be seen together to increase the strength of evidence that comes from these activities. Agreements over evaluation criteria increase the durability of the policy when beneficiaries and administrators adjust to a permanent policy. The real question is: is a reform still defensible when the fiscal costs, distribution, complexity and uncertainty are put on the same page? Good design, therefore, views transparency as a component of policy design and not as a communication exercise after the policy is in place.
Another benefit of this is that the risks of unintended consequences are made apparent before thresholds, exemptions or enforcement rules become entrenched as a matter of routine. The underlying concept is that fiscal design should be tested on actual behavior, not taken for granted based on the fiscal label. This is important because of legal form and economic incidence may change in opposite directions if there is adaptation of households or firms. Another safe practice is to make the assumptions explicit for easy replication and refutation by others.
Evidence is also strengthened when distribution and administration and behaviour are looked at simultaneously and not individually in different reports. Agreements over evaluation criteria increase the durability of the policy when beneficiaries and administrators adjust to a permanent policy.
CITE THIS ARTICLE
Sultana, K. R. (2026). From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance. https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b
K. R. Sultana, “From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance,” 2026. [Online]. Available: https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b
Sultana, K. R. (2026) ‘From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance’. Available at: https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b
Sultana, Kazi Rukaiya. “From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance.” 2026, https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b.
Kazi Rukaiya Sultana. “From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance.” (2026). https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b.
Sultana KR. From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance. 2026. https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b
@misc{article_496925de5a075adbbf9772314895422b,
  title = {From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance},
  author = {Kazi Rukaiya Sultana},
  year = {2026},
  url = {https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b},
}
TY  - GEN
AU  - Kazi Rukaiya Sultana
TI  - From Tax Gap to Compliance Design: Behavioural and Administrative Evidence on Tax gap, fiscal federalism, GST/VAT, tax expenditure, public finance
PY  - 2026-03-18
UR  - https://researchbysultana.com/article/496925de-5a07-5adb-bf97-72314895422b
ER  -
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life