Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy
Kazi Rukaiya Sultana (Master of Public Policy & Master of Social Welfare and Research)
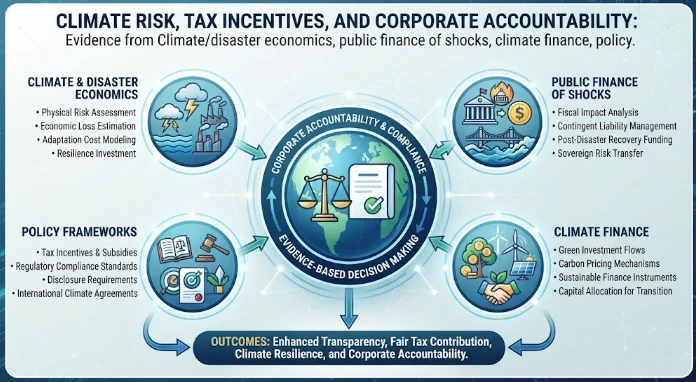
This article treats climate risk as a public-finance and corporate-governance problem shaped by physical hazards, transition policy and fiscal exposure. Floods, heat, storms, droughts and wildfires can reduce revenue while increasing emergency, reconstruction, health and social-protection spending. Disaster economics therefore favours pre-arranged financing through reserves, contingent credit, insurance and risk pools instead of relying only on post-shock improvisation. The article extends this logic to climate finance, where public guarantees, concessional loans, blended finance and tax incentives shift risk between taxpayers and private investors. Distribution matters because energy taxes and climate shocks can burden households differently, while wealthier households may have more capacity to use clean-investment incentives. Climate-adjusted cost-benefit analysis can improve appraisal of resilient infrastructure by including disaster probabilities, network effects and distributional consequences. The article also emphasizes measurable eligibility for green incentives, sunset provisions, additionality tests and credible sustainability reporting. Strong accountability requires transparent fiscal risks, clear performance milestones, consistent tax and environmental data, and evidence that public support produces genuine resilience or emissions benefits rather than merely subsidising existing investment.
Climate risk is now a fiscal and corporate-governance question as physical risks and transition policies can impact the value of assets, operating expenses, insurance access, supply chain, and public budgets. Direct losses due to floods, heat, storms, droughts and wildfires, indirect losses due to decarbonisation policy changes in relative prices of energy, transport, buildings and industry. Carbon pricing, investment allowances, excise design, accelerated depreciation and targeted credit are all part of that adjustment, which is housed within tax systems. A credible framework thus links climate economics to incidence and accountability of taxes, not as a series of one-off environmental concessions.
Disaster economics emphasises the importance of making an investment before a disaster, rather than coming up with a plan after it. To boost liquidity when revenue declines and expenditures increase, budget reserves, contingent credit, insurance, and risk pools can be used. Financial preparedness is long a central component of the World Bank's disaster-risk-financing work and a key tenet of resilience. Climate finance applies the same logic to adaptation and mitigation investment, but requires the ability to set out the allocation of fiscal risk, which needs to be transparent so that the risk is still on the public agenda before climate events are severe.
Critical accounting theory provides an interesting cautionary note on power and framing. Choices over what is disclosed and what is not is not only a fact of life, but also a fact of disclosure. A company may have a falling operational footprint but a growing supply-chain footprint, or show a small 'green' portfolio while a higher-carbon business is unaffected. The definitions, in turn, must be verifiable on tax records, engineering evidence, or accepted reporting practices and be independent of promotional narratives, allowing fiscal authorities to define them.
Climate and disaster economics also upends the public-finance question from the average annual expenditure to tail risk. Major events may result in a compression of tax revenue while emergency expenditure, reconstruction expenditure, health expenditure and social protection needs increase. Disaster risk financing involves the creation of liquidity post-disaster through the use of instruments like reserves, contingent credit facilities, insurance policies, catastrophe cover and reallocation of budget. The goal is not only relief that comes quicker, but it's also preventing disruptive fiscal adjustment when regular revenue falters.
The importance of distribution is related to the fact that climate policy and climate shocks are not necessarily income group or region neutral. Lower income households may find a larger portion of their current income allocated to energy taxes, while wealthy households may be able to dedicate more of their income towards financing an efficient vehicle, insulation, rooftop generation, or other eligible investment. Those imbalances can be abated through targeted transfers, refundable credits and public investment. Household budgets should be used to determine the incidence of an instrument after taxes, prices and compensation payments have been taken into account, and not just from an environmental label.
The same should apply to public investment decisions. Often, resilient infrastructure will be more expensive to build, but will save in losses, service disruption, and reconstruction costs throughout an asset's life. That value may be underestimated in conventional appraisal, if disaster probabilities or network effects or distributional consequences are excluded. Climate-adjusted cost-benefit analysis provides more information for finance ministries to consider when comparing the costs and benefits of prevention to repeated repair. It is still important to make assumptions transparent because the results can be materially affected by projections of hazards and discount rates.
The rationale for climate finance also adds another layer to accountability as the use of public guarantees, concessional loans, blended financing and tax incentives brings with it a redistribution of risk between taxpayers and private investors. This support can open up projects that have high social benefits, while poor contracts can socialize downside risk with most upside retained privately. Fiscal control is reinforced by passing additionality tests, performance milestones, clawback requirements and disclosure of contingent liabilities. When risk sharing is made explicit, it is easier to obtain public support.
Also, public financing of shocks requires distributional planning. A flood or cyclone may simultaneously destroy houses, disrupt employment, impact small enterprises and increase food or transport prices. Outdated registers and time-consuming verification processes may mean that affected households are not reached in time for emergency transfers. Rapid responses can be enhanced by pre-arranged response systems, social protection that can be scaled up and upfront financing rules. Fiscal resilience, therefore, requires a mix of balance-sheet instruments and on-the-ground systems in place to shift resources to impacted people during times of stress.
The horizon of evaluation should be long enough to reflect transition costs and resilience benefits to be linked to firm performance. Energy costs, regulatory exposure or disruption risk can be lowered with environmental investment while capital expenditure in the early stage of an asset's life cycle can lower accounting returns in the short term. This one-year profitability test can result in punishing investments of longterm value. Meanwhile, not all environmental projects have a positive impact on competitiveness, and claims must be based on evidence of productivity, operating cost, revenue quality, financing conditions and risk reduction, not on a blanket sustainability statement.
Other key issues to consider are tax administration for green incentives. Technical requirements like equipment type, emissions intensity, project timing or certification can be a requirement for eligibility. There are expertise and data requirements that go beyond the traditional accounting records which are necessary for revenue agencies, and there are rules needed for documentation that can be relied upon before investment starts for firms. Pre-approval, standardised certificates, information sharing with sector regulators and post-claim verification can help minimise uncertainty. When the qualifying conditions are related to measurable outcomes, then it may be possible to improve the take-up without compromising the integrity of the design through simpler design.
A good climate-tax policy must, therefore, have an exit strategy. The incentive may be appropriate at the time of introduction but later, due to the changing nature of technology, market penetration, carbon pricing or other regulatory factors, may become redundant or become distortive. Price adjustments or eligibility changes through sunset clauses or scheduled evaluation allow for flexibility prior to political commitment to fiscal cost. Review should consider the incentive alongside other policy tools like direct grants, standards, public procurement, carbon pricing or infrastructure investment. What instrument is best isn't necessarily a question of type of tax but, rather, a question of the specific barrier.
Environmental tax incentives can spur investment if they compensate for an identifiable market failure and if the activity that they encourage is clearly specified and carefully designed to minimize windfalls. In the wrong hands, poorly-designed incentives could reward projects that are already commercially viable, incentivize relabelling, or incentivize companies with better tax capacity over companies that offer better environmental benefit. Intersection with grants, investment thresholds, carry-forward rules and refundability affect real access. Evaluation should have an additionality score, an emissions outcome score, a distributional effects score, a fiscal cost score, and an administrative complexity score.
The quality of sustainability information is driving growing corporate accountability. Effective for annual reporting periods starting from 2024, IFRS S1 and IFRS S2 categorize disclosure into four sections: Governance, Strategy, Risk management, Metrics and targets. IFRS S2 differentiates physical climate risk from transition climate risk and relates both to cash flows, access to finance and cost of capital. That's the effect of the architecture – if a green investment incentive is easier to investigate, then it's easier to investigate it – and if capital expenditure, transition plans, and climate exposures are reported consistently, then it's easier to investigate.
Social and environmental accounting takes the analysis beyond the traditional concept of profits. Economic impacts of energy use, emissions, workforce impacts, community exposures, impacts on biodiversity, and remediation requirements may be more indirect than can be observed through a simple financial ratio. Environmental accounting is not a substitute for financial accounting, rather it provides extra information to help determine if external costs are present which are not priced. The combination of tax incentives and this information can help to facilitate the allocation of resources, and, when the measure is weak, turn fiscal support into a branding subsidy.
Consistency in tax records, financial statements, sustainability reporting, investment decisions, and real environmental results is the key to the durable accountability test. When you say you're being green when you're not, you have a credibility risk, and when you say you're propping up green investments without giving an idea of the fiscal costs, you have a credibility risk. Strong policy is grounded in concrete metrics, distributional analysis and public-budget discipline. This mix makes climate taxation symbolic signaling into a quantifiable component of economic transition strategy.
However, the question to be addressed is whether the one is measuring public value when opportunity cost, distribution and compliance costs are added.
CITE THIS ARTICLE
Sultana, K. R. (2025). Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy. https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f
K. R. Sultana, “Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy,” 2025. [Online]. Available: https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f
Sultana, K. R. (2025) ‘Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy’. Available at: https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f
Sultana, Kazi Rukaiya. “Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy.” 2025, https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f.
Kazi Rukaiya Sultana. “Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy.” (2025). https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f.
Sultana KR. Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy. 2025. https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f
@misc{article_03967ebab86b5fb3be4803902118bf9f,
  title = {Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy},
  author = {Kazi Rukaiya Sultana},
  year = {2025},
  url = {https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f},
}
TY  - GEN
AU  - Kazi Rukaiya Sultana
TI  - Climate Risk, Tax Incentives, and Corporate Accountability: Evidence from Climate/disaster economics, public finance of shocks, climate finance, policy
PY  - 2025-10-12
UR  - https://researchbysultana.com/article/03967eba-b86b-5fb3-be48-03902118bf9f
ER  -
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life