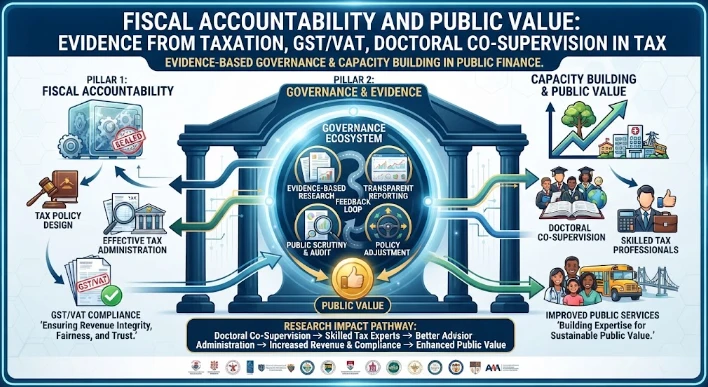
The article frames fiscal accountability around a basic public-value question: what outcomes result from each unit of revenue collected, forgone or spent? It links taxation, GST and VAT administration with governance, professional education and doctoral research. Cross-disciplinary tax research can combine legal doctrine, administrative data, public finance and taxpayer behaviour to test whether rules are coherent, administrable and equitable. The article also argues that tax education should include ethics, administrative justice and public purpose rather than treating minimisation as the only professional objective. Public-benefit accounting is relevant for charities, social enterprises and organisations receiving tax concessions because preferential treatment should correspond with demonstrable public or community outcomes. Fiscal transparency also requires explaining differences between budget forecasts and actual collections, tax gaps and tax-expenditure estimates. Institutional design, independent review and carefully governed data sharing help assign responsibility and strengthen credibility. GST and VAT demonstrate the need to balance timely service with verification of high-risk claims. Broader scorecards should therefore include compliance, taxpayer burden, dispute resolution, staff capability and trust alongside collection efficiency.
The first public-value question of fiscal responsibility is what is the consequence of every dollar of revenue collected and/or spent? Collective priorities are paid for by taxes, exemptions and concessions are allocations through the tax code. Distribution, compliance burden and political legitimacy are impacted by design choices in many cases of GST and VAT, which is a broad-based revenue. Governance is thus linked to revenue performance and transparency, equity and quality of services, and the credibility of revenue and expenditure institutions.
In the field of tax, doctorate co-supervision can help ensure fiscal accountability where research questions relate to legal doctrine and administrative data, public finance and taxpayer behaviour. Cross-disciplinary supervision can be used to validate whether a rule is viable or not – whether it is internally coherent or not. The results of GST compliance or distribution or refund risk research can then be used in training and policy design. Academic independence is necessary because public value is dependent upon the evidence that will be able to challenge the current administrative assumptions.
The norms of teaching also influence professional norms. If students are only taught about the minimisation of obligations, they may see tax as a game where minimising tax is synonymous with making sure they can defend the lowest possible tax bill. Ethics, administrative justice, public finance, governance and the economic function of tax rules can be incorporated into a broad curriculum. It is not a substitute for detailed legal analysis, but rather adds the dimension of technical skills to a broader legal context and impact.
Charities, social enterprises and organisations claiming tax concessions also have similar questions to ask themselves when it comes to public benefit accounting. Qualifying activity typically implies a policy choice that there is social value in the activity. Evidence of accountability in that it must lead to the desired outcome and not be a private gain. Protecting both revenue and public confidence is the protection afforded by reporting rules, governance standards, related party controls, and clear eligibility definitions.
Consistency in budget promises and eventual results is also a part of fiscal transparency. Forecasts are not necessarily the same as collections due to variations in economic growth, price, taxpayer behavior, litigation and policy uptake. Just because something varies from the norm doesn't mean it's a failure. Where there are large differences, external review is improved when authorities clarify these differences, update their assumptions and maintain time series.
Tax gap and tax distribution research can further this explanation. Gap estimates provide information about the extent of under-collection of legal liability, and microsimulation provides information about the impact of tax and transfer policies on households across the income distribution. Those views, when joined together, will help to avoid a narrow focus on revenue. Policy can be effective at efficient collection, but ineffective at burden distribution, or good at burden distribution, but poor at compliance (and hence legitimacy).
The institutional design is important as tax policy and tax administration are spread across ministries, revenue bodies, legislatures, auditors, courts and professional communities. Assigning responsibility minimises duplication and failure can be more easily identified. Independent review/external audit can be used to verify the credibility of internal assurance. Analysis can be enhanced by cross-agency data sharing, but legal protections and purpose limitations still need to be in place.
There are also reasons to be found in the research of GST and VAT why efficiency and fairness must be combined in the same framework. While a wide base can ward off classification issues, pressure for exemptions and lower rates can arise from distributional issues. Where delivery systems are capable, targeted transfers can sometimes help to correct equity without the distortions. The central element of governance quality is to make that trade-off transparent and to assess results when it is put in place.
Good governance also embraces uncertainty. The level of tax expenditure, behavioural impacts and gap in compliance are estimates based on models and imperfect data. Differences in published methodology and ranges of uncertainty can be used to allow for informed differences without credibility crises. However, communicating the limitations can enhance trust as the stakeholders are able to differentiate between what is measured and what is assumed.
Much of that accountability is expressed in a language that is provided by accounting. Tax revenue, tax receivables, tax provisions, tax transfers and the public assets are included in financial statements, whereas budget documents provide explanations of policy decisions and forecasts. Tax-expenditure statements complement the picture with an indication of revenue lost because of preferential provisions. If it is not available, a government may increase its fiscal support by increasing taxes, while the expenditure figures don't reflect the increase.
The two other examples are GST and VAT which illustrate administrative performance. Exemptions, thresholds, refunds and sector rules place pressure on the broad bases and invoice trails which facilitate efficient collection. Delays in refunds can have a negative effect on business cash flow, and inadequate verification can allow considerable revenue to leak through. Public value is about recognizing the importance of providing timely service to compliant firms whilst implementing focused measures against the high-risk claims.
The OECD Tax Administration series has increasingly become about designing non-compliance, and burden, out of routine processes, through the lens of digitalisation. If systems are dependable, they can minimise friction through reduced need for pre-filled data, online accounts and standardised reporting and analytics. Governance of privacy, cybersecurity, access, procurement and algorithmic decisions still need to be addressed for digital transformation. Technical improvements that are hidden, or exclude those taxpayers who cannot access digital channels lose their public purpose.
Past performance measurement should be placed on a different footing – moving it away from cost-of-collection ratios. The low administrative cost may be indicative of efficiency, but it may also be indicative of the fact that there are gaps or that the service is not good or that there is under-investment at the administrative level in complex situations. Revenue assurance, voluntary compliance, processing time, dispute resolution, taxpayer burden, staff capability, and trust are examples of good scorecards. The quality of a tax administration can't be expressed by a single indicator.
Education and research help to reinforce accountability through the enhancement of professional judgment. Advanced taxation is a law, economics, accounting, data, ethics and institutional design exercise and therefore a narrow technical training can overlook important consequences. Doctoral supervision and research communities serve as a test of assumptions, assessment of policy, and development of approaches to issues like tax gaps, distributional incidence, and tax compliance behavior. Public value increases when that research becomes public, in the form of transparent evidence—not just trapped in academic publication.
For the first time fiscal accountability relies on feedback. Rules can have unexpected costs, as demonstrated by evidence from administration, courts, clinics, businesses, researchers and communities. Evidence should drive evaluation to simplification, re-designed thresholds, improved guidance or increased controls. Public value is not achieved through the highest possible collection rate, regardless of the means, but by maintaining a fair and transparent and sustainable revenue system to support the legitimate public purpose.
Evidence also gets better when distribution, administration and behaviour are studied in combination and not in isolated activities in separate reports. Evaluating and agreeing upon criteria in advance of beneficiaries and administrators adapting around a permanent policy promotes policy durability. The only real litmus test is whether a reform is still defendable if you balance its fiscal cost, distribution, complexity and uncertainty on the same plane. Good design thus does not just involve communicating the transparency of a policy after it has been put in place but as a part of the policy architecture.
The other benefit of this is that hidden trade-offs are evident before thresholds and exemptions become the routine. The broader message is that the structure of the fiscal policy should be analysed based on observed behaviour, not on descriptive labels. This is important because the legal form and the economic incidence may go in different directions once households or firms adjust. Another way of providing this protection is to state the assumptions clearly, so that an independent analysis can be done or the central result challenged.
The strength of the evidence is increased if it is looked at in terms of distribution, administration and behaviour, rather than each of those separately in separate reports. Evaluating and agreeing upon criteria in advance of beneficiaries and administrators adapting around a permanent policy promotes policy durability. The test for defendability of a reform is whether it survives when fiscal costs, distribution, complexity and uncertainty are brought to the same table. Good design thus does not just involve communicating the transparency of a policy after it has been put in place but as a part of the policy architecture.
One benefit of this is that any hidden trade-offs become apparent before thresholds, exemptions or enforcement settings are ingrained in the routine. The more profound message is that fiscal design should be subjected to empirical observation, not to implicit assumptions based on labels in the law. This distinction is important because the legal and economic incidence may go in opposite directions after adjustment by the household or firm.
CITE THIS ARTICLE
Sultana, K. R. (2026). Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax. https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5
K. R. Sultana, “Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax,” 2026. [Online]. Available: https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5
Sultana, K. R. (2026) ‘Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax’. Available at: https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5
Sultana, Kazi Rukaiya. “Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax.” 2026, https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5.
Kazi Rukaiya Sultana. “Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax.” (2026). https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5.
Sultana KR. Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax. 2026. https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5
@misc{article_faa7dfc383a95cab9eae2726dbbab1b5,
  title = {Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax},
  author = {Kazi Rukaiya Sultana},
  year = {2026},
  url = {https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5},
}
TY  - GEN
AU  - Kazi Rukaiya Sultana
TI  - Fiscal Accountability and Public Value: Governance Evidence from Taxation, GST/VAT, doctoral co-supervision in tax
PY  - 2026-02-18
UR  - https://researchbysultana.com/article/faa7dfc3-83a9-5cab-9eae-2726dbbab1b5
ER  -
This article uses institutional economics and applied microeconomics to show why tax-transfer reform cannot be evaluated from policy rules alone. Household disposable income reflects earnings, taxes, contributions, benefits, housing support and withdrawal schedules, but the effectiveness of those rules also depends on institutions that administer them. Different data systems, delayed appeals, inconsistent local delivery and administrative capacity can cause a theoretically efficient policy to wo
This article presents tax transparency as a governance and accounting issue rather than a simple disclosure exercise. Boards oversee tax outcomes that are influenced by risk appetite, capital allocation, internal controls, remuneration and significant transactions, while accounting systems provide the common record connecting financial profit, taxable income, deferred tax, cash tax and uncertain positions. IFRS S1 and IFRS S2 are used to show how sustainability-related financial information can
This article evaluates tax expenditures in not-for-profit, charity and resource-tax settings through distribution, governance and public value. Preferential treatment for charities and similar organisations is justified by public or community benefit, so reporting and governance should show whether concessions expand valued services, improve access or instead accumulate as private or organisational advantage. The article warns that annual income alone is an incomplete equity measure because life