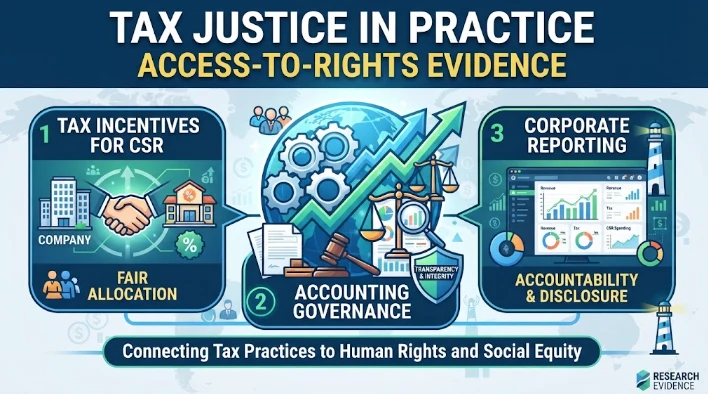
Governments often use tax incentives to promote socially desirable behaviours. Deductions, credits, accelerated allowances, exemptions and preferential treatment can help to support charitable giving, research, investment in the environment, employee development, community projects or other corporate activities related to social responsibility. The appeal of this is obvious: if the government does not have to pay for every programme, it can change the cost of private programmes to the government, that is, the tax price. But there is a tougher question about tax justice. If a business is benefiting from a "socially responsible" activity, what is the evidence that the public is benefiting from the company?
The solution starts with a tax expenditure. Although no cash grant may be listed in the spending budget, it has a fiscal cost if it is a concession that reduces liability compared to a benchmark tax system. The cost of that is more easily disguised than a direct appropriation, which could help make it less subject to scrutiny.
A deduction for qualifying activity, for instance, lowers the revenue and alters the tax incentives of the claimant; and the benefit of such a deduction will depend on the tax situation of the claimant and the exact nature of the deduction. A deduction which is not refundable does not provide any immediate benefit to a company with losses while it does provide an immediate benefit to a company with profits. Distribution is important in addition to the policy goal.
The corporate social responsibility dimension is further added because of the wide range of activities that have very different relationships with core business strategy. Some initiatives focus on real social or environmental effects that are caused by production, supply chains, jobs or use of resources. Others are like philanthropy, marketing or reputation management.
If all CSR expenditures are considered the same, then a tax shield could be available for limited social value added. Well-designed policies begin with a clear policy goal, definition of eligible costs, evidence standard, and tests of additionality. Public support should be for more than the usual "legal" obligations, and not for activities that would happen anyway.
Additionality is difficult to prove, but the question cannot be avoided. If there are statutory conditions that are met, a company that installs an energy-efficiency improvement for business purposes is entitled to a green tax incentive. The policy question is whether the incentive shifted in terms of timing, scale, type of technology adopted, or investment location.
The same issues come into play when it comes to training credits, research incentives, or community-investment concessions. An easy going incentive without evaluation can become a windfall for existing behaviour. Tax justice must consider opportunity cost because every dollar of foregone taxes could be used for another tax cut, transfer, public service or investment.
Accounting governance is the structure which facilitates that evaluation. There must be a clear understanding of what is considered qualifying expenditure across boards, audit committees, finance teams, sustainability functions and tax departments, and solid controls on claims. Documentation should reflect activity, qualification for the tax benefit, cost to entity, and calculation of the tax benefit. Weak controls can result in both compliance risk from weak controls and false claims of sustainability. The tax-supported initiative cannot be taken as proof of social responsibility if it is not supported by internal records of the company.
Financial and non-financial information can help to enhance accountability in corporate reporting. Sustainability reports may contain information on emissions reduction, workforce programmes, community investment or social impact projects, whereas tax notes may be used in technical accounting terminology to describe incentives. Creating a distinction between those narratives can make the public contribution to an initiative invisible. Improved reporting is provided that outlines the material government support, the activity undertaken as a result of that support and the outcomes that were achieved as a result of that activity. The goal is not to share all the tax calculations, but to communicate meaningfully with investors, communities and policymakers about key public-private arrangements.
Transparency of tax standards further reinforces that direction. GRI 207: Tax included disclosures related to tax strategy, governance, engagement with stakeholders and country by country reporting. The standard approach to tax is to consider it a sustainability issue since tax payments are a funding source for institutions and services.
That framing establishes a fascinating symmetry. In considering corporate contribution, the large tax concessions should be evident as part of social contribution. The gross amount of taxes paid does not necessarily show a high fiscal contribution if they are paid under significant incentives which can lower the actual fiscal burden.
The rights-based analysis further highlights the point. Health, education, housing support, infrastructure, environment protection and other functions related to social wellbeing are funded by public revenue. Tax incentive is a transfer of the state's fiscal power to a selected activity.
A decision may be made for this reason, but it is better to be legitimate if there is clarity about the goal, the cost, the recipients and the results. A concession with weak evidence can diminish the resources for the delivery of programmes for less influential groups. Tax justice thus involves both who's eligible to be taxed and who gains from the missed tax yields.
Not all direct spending is necessarily better. Tax incentives can leverage existing business systems, can automatically respond to qualifying activity and can minimize the need to pick and choose qualifying grants. The wide eligibility can reduce the likelihood of political favouritism.
The direct spending, however, can be directed towards non-taxing entities, can have total cost more easily capped, and can have explicit conditions attached to its performance. The instrument used will vary according to the objective. A tax incentive should be considered in the context of a grant, regulation, procurement condition and/or direct public investment rather than assuming that it is the natural way forward for a fiscal concession.
Sunset provisions and periodic reviews can enhance discipline. A market change can take place after the enactment of an incentive, and it may stay on the books. Take-up, fiscal cost, further investment, distribution by size and industry, environmental or social outcomes, administration hassles and evidence of gaming should all be evaluated regularly. Where beneficiaries have developed expectations around a programme based on its performance, it should be re-designed or terminated if it is not doing well. Tax expenditure should be treated seriously like the direct spending programmes.
Anti-avoidance design is also a factor. On the positive side, CSR incentives that are very general may lead to rewording of normal business costs. Fiscal leakage can occur due to related party transactions, over-value transactions, artificial separability of projects, or double claims across programmes.
That risk is lessened through clear boundaries, third-party evidence, audit trails and data matching. In addition, the controls should be proportionate, as overly complex systems may deter small businesses from joining. A scheme with an unintended distributional bias can be created by a scheme that is only accessible to larger companies with specialist advisers.
The conflict between claims for incentives and responsible tax strategy also needs to be considered in the context of corporate governance. A legislated incentive isn't a bad idea for the aggressiveness alone. Governments are establishing incentives to actually change behaviour.
Governance question: Do claims accurately reflect the purpose of the policy, the economic character of a policy and the disclosed risk appetite? Boards need to be aware of material incentives, particularly when a concession is a key component of the effective tax rate, or the sustainability story. It is important that the tax returns, financial statements and public statements remain consistent with each other.
The quality of the programme could be enhanced through stakeholder scrutiny. Tax risk and environmental commitments and governance are considered in tandem and more integral to the investment decision, and civil-society organisations are more likely to consider fiscal contribution and distribution. Communities with subsidised investment have the option to question if jobs, environmental enhancements, or neighborhood benefits actually materialise. Public agencies can share aggregated information on programme cost and outcomes without revealing sensitive information about taxpayers. This clarity makes tax incentives from policy instruments tangible public promises.
The strongest argument for tax incentives for corporate responsibility is on the basis of evidence, not branding, by 24-05-2026. Supporting an investment that has a social value is a fiscal concession, but a social value does not exist because an expense has a CSR label. To ensure tax justice, there should be a clear goal, increased activity, trustworthy accountancy, board oversight, clear reporting and periodic review of tax revenues against other revenue sources. When companies provide explanations for tax contributions and tax support, it makes the corporate responsibility more credible. The more government spending is held accountable for its outcomes, the more so should be the case for tax expenditures.Whereas direct government spending is subject to the same questions – what changed, who benefitted, and was it worth the public cost? – so should be the case with tax expenditures.